India-Mauritius DTAA Amended to Prevent Tax Avoidance and Treaty Abuse: New Article 27B Introduces Anti-Abuse Rules:
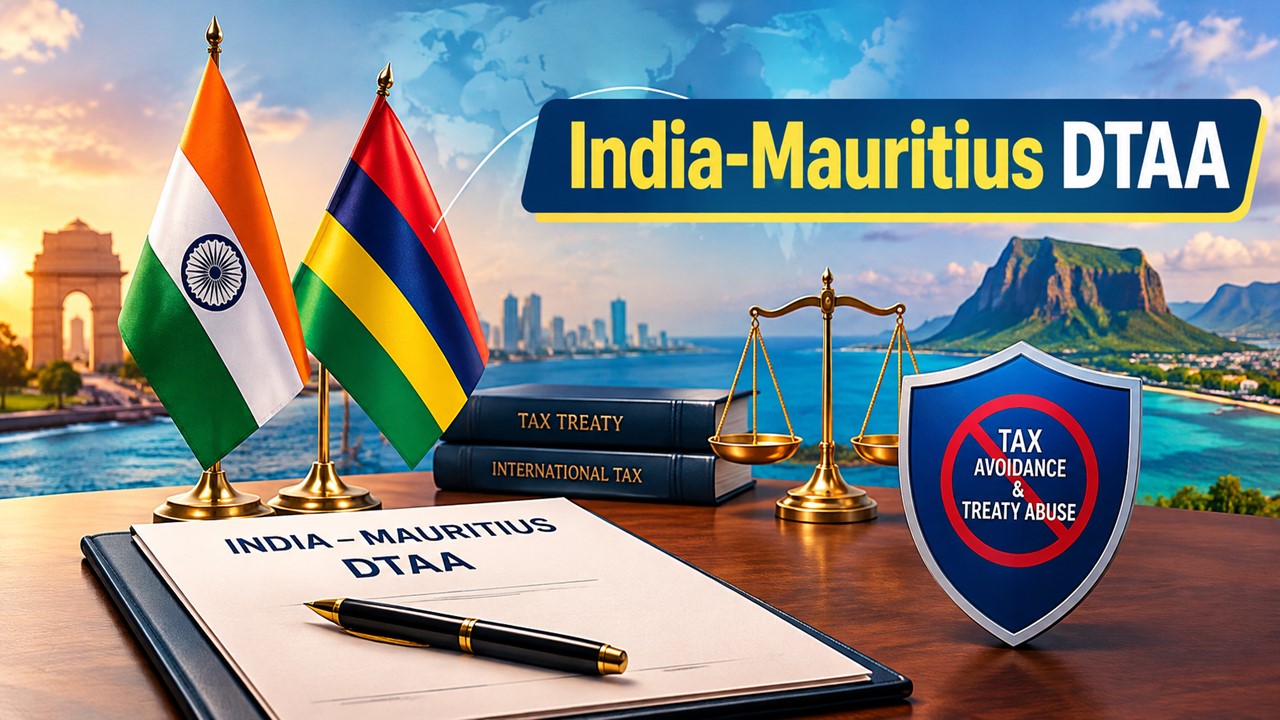
The Ministry of Finance has notified amendments to the India-Mauritius tax treaty, introducing Article 27B to deny treaty benefits in certain arrangements where obtaining such benefits was one of the principal purposes.
India-Mauritius Tax Treaty Protocol Takes Effect from August 10, 2026
 Saloni Kumari
 Oct 15, 2026

The Ministry of Finance (Department of Revenue) has released a notification dated October 13, 2026, notifying all the provisions of the Protocol amending the Double Taxation Avoidance Convention (DTAC) between the Government of the Republic of India and the Government of Mauritius for the purpose of avoiding double taxation and curbing fiscal evasion.
The central government has issued this notification in exercise of its powers granted under Section 159(1) of the Income-tax Act, 2025, to give effect to the amendments introduced through the Protocol signed at Port Louis on March 7, 2024.

The Protocol had come into force on August 10, 2026, following the completion of the required legal procedures by both countries. These amendments are aimed towards preventing double taxation while ensuring that the tax treaty is not misused to obtain unintended tax benefits through tax avoidance, tax evasion or treaty-shopping arrangements.
A key amendment replaces the existing preamble of the Convention. The revised preamble clarifies that the treaty is intended to eliminate double taxation without creating opportunities for non-taxation or reduced taxation through tax evasion or avoidance. It specifically addresses arrangements designed to obtain treaty benefits indirectly for residents of third countries.

The Protocol also introduces a new Article 27B titled “Entitlement to Benefits” after Article 27A of the Convention. Under this provision, treaty benefits may be denied for an item of income if, considering all relevant facts and circumstances, it is reasonable to conclude that obtaining such benefits was one of the principal purposes of an arrangement or transaction.
However, treaty benefits may still be granted if it is established that allowing them would be consistent with the objectives and purpose of the relevant treaty provisions. The convention has been amended by inserting after Article 27A the following new Article: “Article 27B ENTITLEMENT TO BENEFITS Notwithstanding the other provisions of this Convention, a benefit under this Convention shall not be granted in respect of an item of income if it is reasonable to conclude, having regard to all relevant facts and circumstances, that obtaining that benefit was one of the principal purposes of any arrangement or transaction that resulted directly or indirectly in that benefit, unless it is established that granting that benefit in these circumstances would be in accordance with the object and purpose of the relevant provisions of this Convention.”
As per Article 3 of the Protocol, the amendments take effect from August 10, 2026, irrespective of when the taxes are levied or the relevant tax years to which they relate. The changes strengthen safeguards against treaty misuse while preserving the objective of preventing double taxation between India and Mauritius.
About Author

Saloni Kumari
Content Writer
 StudyCafe
 Delhi, Delhi, India
 2910
My Recent Articles
- ICAI Announces Result Declaration Date for CA Intermediate September 2026 Exam
- ICAI Publishes Detailed Recommendations of 57th GST Council Meeting Held on October 8, 2026
- JK Tyre & Industries Receives GST Show Cause Notice of Rs 94.86 Crore Over ITC and Tax Classification Issues
- GSTR-9 and GSTR-9C Filing Enabled for FY 2025-26 on GST Portal; GSTN Introduces Helpdesk for Filing Assistance
- Form ADT-1 Filing Due Today: Companies Must Complete Filing by October 14 for Auditor Appointments Made on September 30
Loading suggestions…