ITAT Reduces Bogus Purchase Disallowance from 20% to 7% in Civil Contractor's Case for Two Assessment Years:
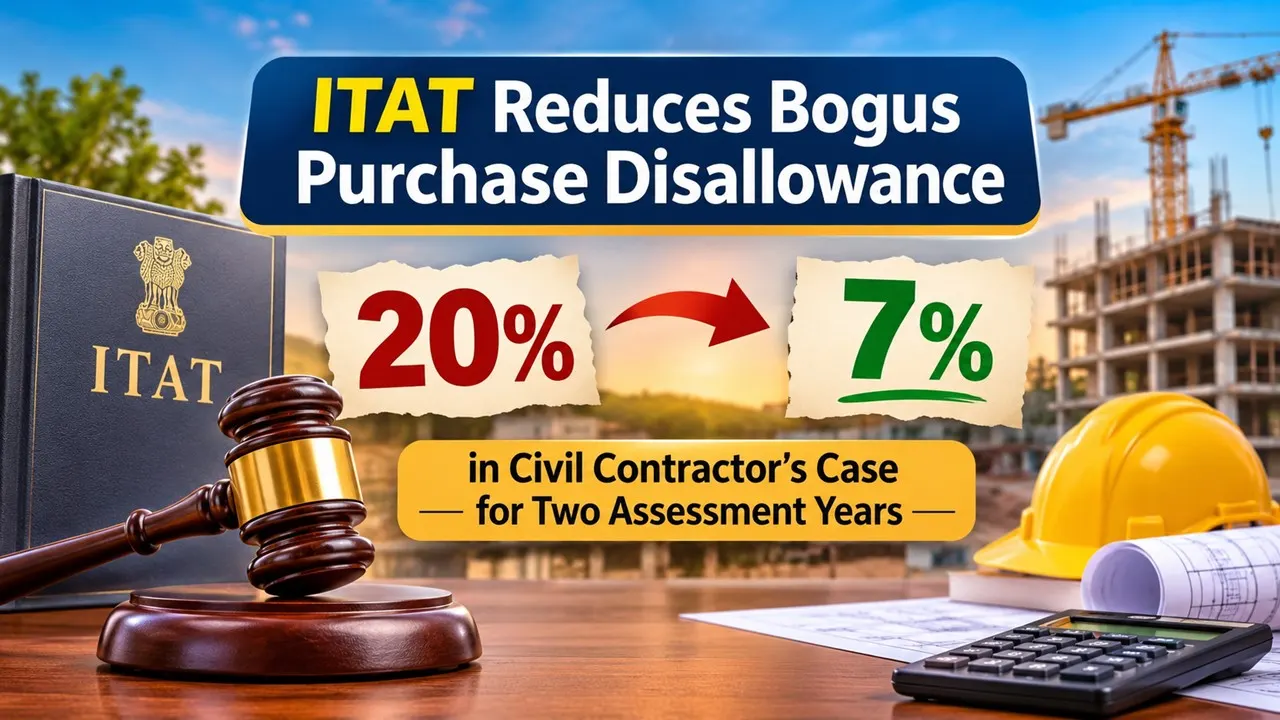
The ITAT reduced the disallowance on alleged bogus purchases from 20% to 7% for AY 2019-20 and 2020-21, granting partial relief to Pureways Infra Pvt. Ltd.
ITAT Holds 7% Disallowance Appropriate on Alleged Bogus Purchases Instead of 20%
 Saloni Kumari
 Nov 13, 2026

The Income Tax Appellate Tribunal (ITAT), Delhi Bench, has reduced the disallowance on alleged bogus purchases from 20% to 7% in the case of Pureways Infra Pvt. Ltd. for Assessment Years 2019-20 and 2020-21. The Tribunal held that neither the assessee had adequately explained the purchases nor could the Department disregard the supporting evidence altogether.
The assessee, engaged in civil construction contracts, filed its income tax return for AY 2019-20, declaring a total income of Rs 2.09 crore. During assessment proceedings, the Assessing Officer (AO) made an addition of Rs 1.28 crore under Section 69C of the Income Tax Act, treating certain purchases as unexplained expenditure.

Aggrieved by the decision, Pureways Infra approached the Tribunal, arguing that it had submitted complete supporting documents for the purchases. It also contended that the purchases from entities allegedly linked to Sanjay Jain could not be treated as bogus without establishing any cash trail or proving that money was returned to the assessee. Further, it argued that its books were audited and no defects had been identified by the AO. The Revenue, on the other hand, supported the AO's order.
After examining the submissions, the Tribunal observed that "the AO has not brought any material on record to show that the assessee had any alternate source of income or funds to incur the said expenditure outside the books. In the absence of such findings, the Ld. CIT(A) has held that application of section 69C is not justified in the present case, thus, Ld. CIT(A) sustained the same only u/s. 37 of the Act, after excluding the GST component by sustaining the addition of Rs 20,44,448/- being 20% of the disputed purchases of Rs 1,02,22,241/-."

Considering the facts of the case, the Tribunal held that a disallowance of 7% of the disputed purchases would be appropriate instead of the 20% sustained by the CIT(A). Accordingly, the addition was reduced, with the necessary computation to be carried out as per law.
The Tribunal applied the same decision to AY 2020-21 and partly allowed both appeals filed by the assessee. Consequently, the Revenue's cross-appeals for both assessment years were dismissed as infructuous. The order was pronounced on November 3, 2026.
About Author


Saloni Kumari
Content Writer
 StudyCafe
 Delhi, Delhi, India
 3048
My Recent Articles
- Rane Holdings Subsidiary Gets Relief as GST Authorities Withdraw Rs 11.88 Crore Demand
- MCA Reminds Companies of November 29 Deadline to File PAS-6 for September 2026 Half-Year
- ITAT Restricts Bogus Purchase Disallowance to 1%, Slashes Addition from Rs 50.95 Lakh to Rs 50,950
- ITAT Deletes Rs 53.76 Lakh Addition, Holds Additional Compensation for Compulsory Acquisition of Agricultural Land Tax-Exempt
- Madras HC Upholds Mahindra Holidays’ Revenue Deferral Methodology, Cuts Contingent Liability by Rs 106 Crore
Loading suggestions…


Recent Posts
All Posts
Recent Posts
All Posts