AAR Denies 5% GST Benefit on Aquaculture Aerator Gear Boxes and Separately Supplied Spare Parts:
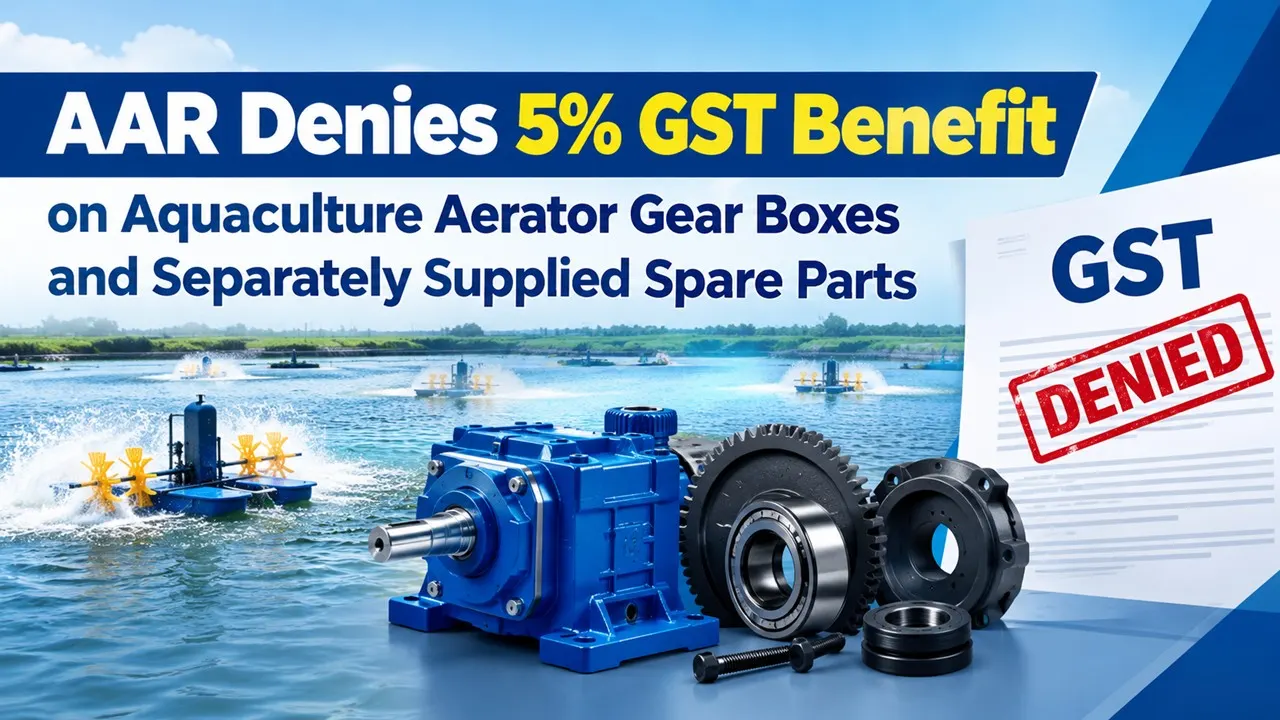
Tamil Nadu AAR classifies aquaculture aerator gear boxes under HSN 84834000, making them subject to 18% GST instead of the claimed 5% concessional rate.
AAR Rules 18% GST on Aerator Gear Boxes
 Vanshika verma
 Sep 21, 2026

BAS-J Industries has sought a ruling from the Tamil Nadu Authority for Advance Ruling (AAR) on the classification and GST rate applicable to aerator gear boxes used in aquaculture aerator machinery.
The applicant is engaged in factory/manufacturing, wholesale business and retail business. The dispute concerned the classification of aerator gear boxes used in aquaculture aerator machinery and whether the goods and their spare parts could qualify for the concessional GST rate of 5% applicable to specified agricultural machinery.

Questions Raised
"1. The product classifiable under HSN 84368090 ("Other Agricultural Machinery") as per the First Schedule to the Customs Tariff Act, 1975 (made applicable to GST classification under Section 9 of the CGST Act read with Section 5 of the IGST Act), is covered under Entry No. 434 of Schedule-I of Notification No. 9/2025-Central Tax (Rate) dated 17.09.2025, and accordingly attracts GST at the rate of 5% (2.5% CGST + 2.5% SGST).
2. That the Spare parts, components, and accessories used in, or supplied for growing of prawns which are essential for, or form part of, the prawn farming aerator machinery falling under HSN 84368090 ("Other Agricultural Machinery") - are also eligible to be taxed at the same rate of 5% (2.5% CGST + 2.5% SGST) in terms of the principle that parts of goods are classified and taxed in accordance with the classification of the main equipment, unless specifically excluded, thereby falling under Entry No. 434 of Schedule-I of Notification No. 9/2025-Central Tax(Rate) dated 17.09.2025."

AAR Ruling
The Tamil Nadu AAR, however, rejected the applicant's proposed classification of the aerator gear boxes under HSN 8436.
The Authority ruled that aerator gear boxes supplied by the applicant do not merit classification under HSN 8436 and therefore do not qualify for the 5% GST rate under Serial No. 434 of Schedule-I of the relevant notification.
Instead, the AAR held that the aerator gear boxes are classifiable under HSN 84834000 and would attract GST at 18%.
The Authority also ruled on the spare parts of the gear boxes when supplied separately. Such spare parts, according to the ruling, do not merit classification under HSN 8436 and therefore would not qualify for the 5% rate.
The spare parts, when supplied separately, would instead attract GST at 18% under HSN 84839000.
About Author

Vanshika verma
Content Writer
 Studycafe
 Delhi, Delhi, India
 2103
My Recent Articles
- Income Tax Department Suspects Rs 5,121 Crore Tax Evasion in Uttar Pradesh After Examining Over 26,000 Property Registration Documents
- Kalpataru Properties Gets Rs 73.85 Crore GST Notice, Says No Material Impact Expected
- Amara Raja Energy And Mobility Faces Rs 1.89 Crore GST Demand as Meerut Appellate Authority Upholds Earlier Tax Order
- Taj Hotels Operator IHCL Fined Rs 10 Lakh by BMC for Alleged Failure to Obtain NOC for Building Plan Approval
- Centre Hikes Windfall Tax on Petrol Exports to Rs 2.5 per Litre, Cuts Diesel Export Duty to Rs 8.5
Loading suggestions…


Recent Posts
All Posts
Tags
Recent Posts
All Posts