ITAT Remands Rs 1.83 Crore Section 10(26AAA) Sikkim Old Settler Tax Exemption Dispute After Condoning 2,027-Day Delay:
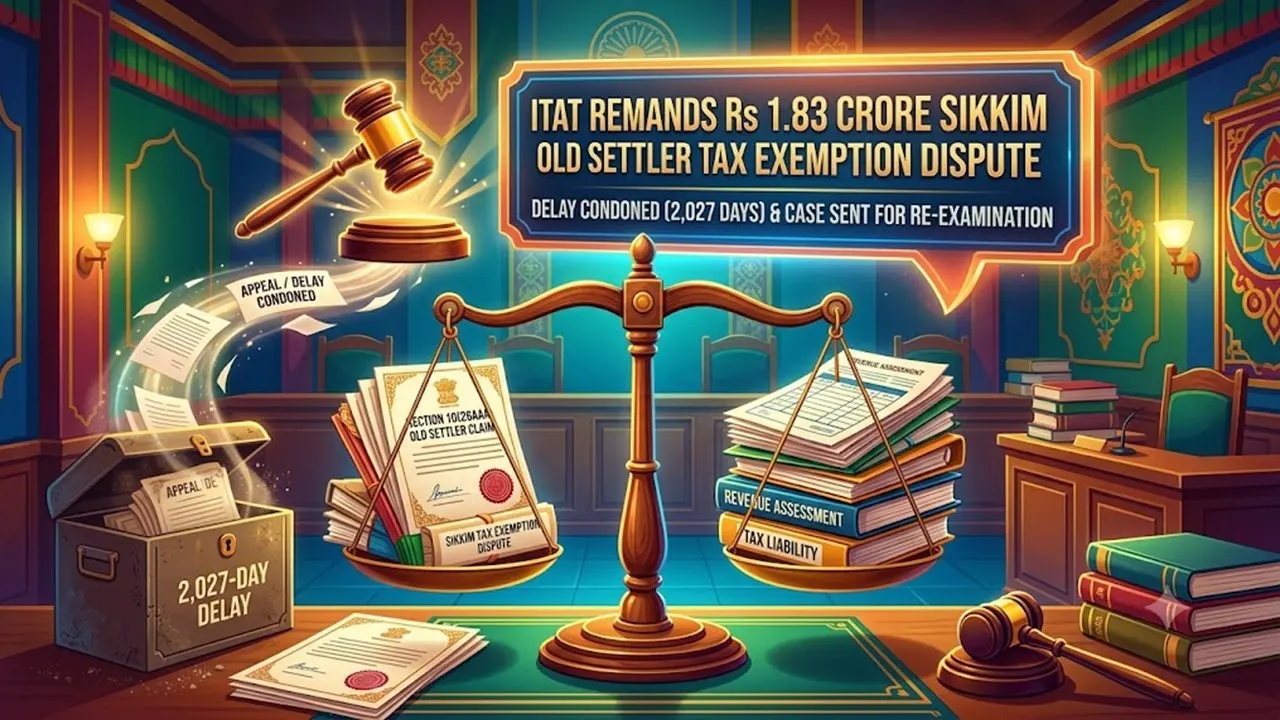
ITAT condoned a 2,027-day delay and remanded Section 10(26AAA) Sikkim Old Settler exemption dispute for fresh adjudication by the AO.
ITAT Restores Five Appeals to AO
 Saloni Kumari
 Sep 29, 2026

The Income Tax Appellate Tribunal (ITAT), Kolkata Bench, has remanded the tax exemption dispute of Sunil Kumar Agarwal for Assessment Years (AYs) 2011-12 to 2015-16 to the Assessing Officer (AO) for fresh consideration. The Tribunal also condoned a delay of 2,027 days in filing the appeals, finding the reasons given by the assessee to be genuine.
The assessee had declared nil income, claiming exemption under Section 10(26AAA) of the Income Tax Act on the ground that he was a resident of Sikkim and an “Old Settler” of the state by birth. However, the AO completed the assessments under Sections 144 and 147 and denied the exemption, making an addition of Rs. 1.83 crore for AY 2011-12. The Commissioner of Income Tax (Appeals) [CIT(A)] subsequently upheld the addition.

Before the ITAT, the assessee submitted that the issue of eligibility of Old Settlers of Sikkim had been addressed by the Supreme Court and that the Income Tax Act was subsequently amended with retrospective effect from 1990-91. The assessee requested that the matter be sent back to the AO for reconsideration in light of the Supreme Court’s decision.
The Tribunal noted that a coordinate bench had taken a similar view in the case of Sanjay Kumar Agarwal and had directed the AO to reconsider the matter after applying the principles laid down by the Supreme Court concerning Old Settlers of Sikkim.

Accordingly, the ITAT restored all five appeals to the AO for fresh adjudication after providing the assessee a reasonable opportunity of being heard. The appeals for AYs 2011-12 to 2015-16 were allowed for statistical purposes.
About Author


Saloni Kumari
Content Writer
 StudyCafe
 Delhi, Delhi, India
 2937
My Recent Articles
- ITAT Upholds Rs 2.76 Lakh Addition, Holds Stock Exchange and Banking Records Alone Cannot Prove Genuine LTCG
- ITAT Deletes Rs 1.80 Crore Addition, Holds Asset Revaluation Does Not Mean Fresh Investment
- ITAT Denies Rs 1.90 Lakh Section 80GGC Deduction Over Donation to Apna Desh Party, Relies on Supreme Court Judgement
- ITAT Deletes Rs 10.76 Lakh Expense Disallowance, Remands Rs 17.66 Lakh Cash Payment Issue
- ITAT Quashes Bogus LTCG Assessment for Non-Service of Mandatory Section 143(2) Notice
Loading suggestions…


Recent Posts
All Posts
Recent Posts
All Posts