CBDT Extends Income Tax Return and Tax Audit Report Filing Deadlines for AY 2026-27:
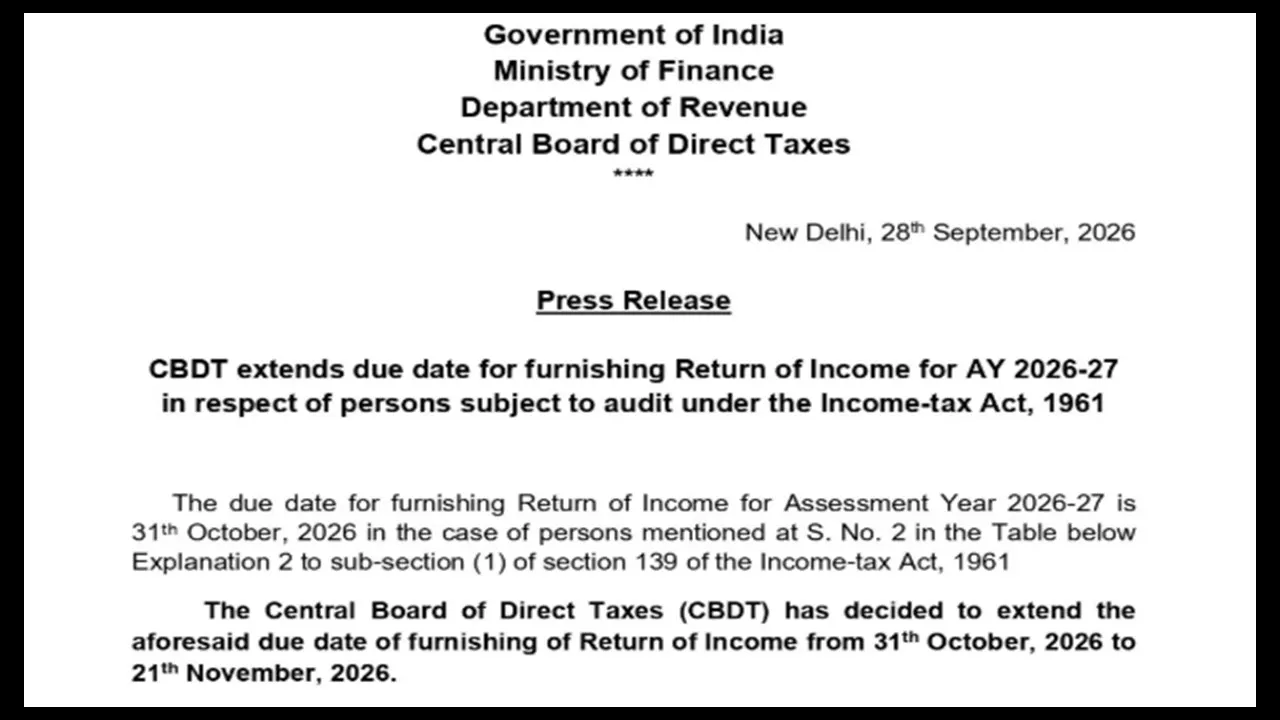
CBDT has extended the ITR filing deadline for taxpayers subject to audit to November 21, 2026, and the tax audit report deadline to October 21, 2026, for AY 2026-27.
CBDT Extends ITR Filing Deadline for Audit Cases
 Saloni Kumari
 Sep 28, 2026

The Central Board of Direct Taxes (CBDT), Ministry of Finance (Department of Revenue), has extended the due date for filing the Income Tax Return (ITR) for audit cases and Tax Audit Report (TAR) for the Assessment Year 2026-27 (Financial Year 2025-26).
The Income Tax Department has extended the due date for filing returns of income for the taxpayers subject to audit under the Income Tax Act 1961 from October 31, 2026, to November 21, 2026.

Correspondingly, the "specified date" to furnish the tax audit report under the Income Tax Act 1961 has been extended from September 30, 2026, to October 21, 2026.
This extension pertains to the taxpayers referred to at Serial Number 2, in the Table below, Explanation 2 to sub-section (1) of section 139 of the Income Tax Act 1961.

The aforementioned extensions in the ITR and TAR deadlines have been officially announced by the CBDT through a press release dated September 28, 2026, which has also released an official notification notifying the same.
The Central Board of Direct Taxes (CBDT) has decided to extend the due date of furnishing of Return of Income for Assessment Year 2026-27 in the case of persons mentioned at S. No. 2 in the Table below Explanation 2 to sub-section (1) of section 139 of the Income-tax Act, 1961… pic.twitter.com/wyLzVBXSNY
— September 28, 2026
Updated Due Dates:
Type | Deadline | Fees |
ITR-1, ITR-2, ITR-7 (No Business or Audit) | 31 July 2026 | Check Belated ITR Fees |
ITR-3, ITR-4, ITR-5, ITR-7 – Business Income, No audit | 31 August 2026 | Check Belated ITR Fees |
ITR-3, ITR-5, ITR-7 - With mandatory audit | 21 November 2026 | None; original filing due date |
ITR-6 | 21 November 2026 | None; original filing due date |
Tax Audit (Form 3CA/3CB-3CD, 10B and 10BB) | 21 October 2026 | None; original filing due date |
Company AGM Due Date | 30th September |
|
AOC-4 | 30th October | None; original filing due date |
MGT-7 | 29th November | None; original filing due date |
Belated ITR | 31 December 2026 | ₹5,000 (income > ₹5 lakh) or ₹1,000 (income upto ₹5 lakh) Loss: Can't carry forward losses |
Revised ITR – To correct errors in an already filed ITR | 31 March 2027 | None till 31 December; thereafter ₹5,000 (income > ₹5 lakh) or ₹1,000 (income upto ₹5 lakh) |
Updated ITR – Voluntary disclosure of past missed income | 48 months from end of AY of missed income. AY 2022-23 to AY 2025-26 covered this year | Additional tax on tax + interest due if filed within: 0–12 months → 25%; 12–24 months → 50%; 24–36 months → 60%; 36–48 months → 70% |
Based on CBDT Press Release dated 28.09.2026
About Author


Saloni Kumari
Content Writer
 StudyCafe
 Delhi, Delhi, India
 3034
My Recent Articles
- Delhi-NCR Couple Under Scanner for Alleged Rs 5.3 Crore Tax Evasion Using Fake Receipts and Fabricated Certificates
- RBI Announces Extension in Supersession of Board of Directors of Abhyudaya Co-operative Bank for Another Year
- ITAT Cancels Section 271D Penalty on Rs 47.54 Lakh Cash Property Sale Over Invocation of Wrong Income Tax Section
- BHEL Gets Major Relief as GST Department Drops Rs 207.26 Crore Demand for FY 2022-23
- Hyderabad Investment Fraud: Man Allegedly Cheats 7,400 Investors of Rs 670 Crore by Promising 4% Monthly Returns
Loading suggestions…


Recent Posts
All Posts
Recent Posts
All Posts