Section 148 Notice Without Manual or Digital Signature Invalidates Entire Reassessment Proceedings, Holds ITAT:
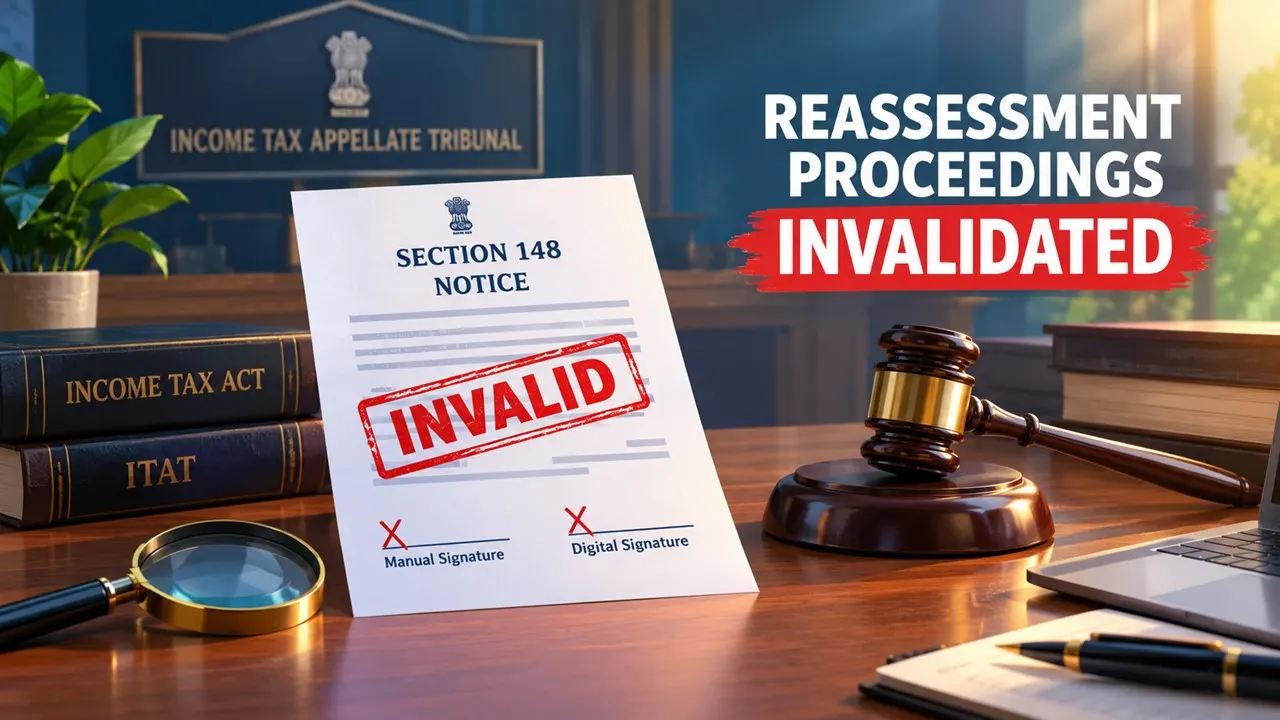
The ITAT quashed reassessment proceedings, holding that an unsigned Section 148 notice was invalid and could not confer jurisdiction on the AO.
Rs 63.29 Lakh LTCG Addition Quashed
 Saloni Kumari
 Oct 22, 2026

The ITAT Hyderabad Bench invalidated the entire reassessment proceedings for the Assessment Year 2015-16 after noting that the Section 148 notice was not signed by the Assessing Officer (AO), neither manually nor digitally.
The case of Shri Venkata Padmavathi Dalapathirao (Assessee) was reopened by the Assessing Officer (AO) and, vide the assessment order dated December 27, 2018, passed under Section 143(3) read with Section 147 of the Act, an addition amounting to Rs 63.29 lakh towards long-term capital gains (LTCGs) arising from the sale of immovable property.

The assessee, being aggrieved by the AO's order, had challenged the same before the Commissioner of Income Tax (Appeals) [CIT(A)]; however, the impugned addition was sustained. Subsequent to this, the assessee approached the Income Tax Appellate Tribunal (ITAT).
Before the ITAT, the assessee challenged the validity of the reassessment proceedings, arguing that the notice issued under Section 148 did not contain either a manual or digital signature of the Assessing Officer. The assessee relied on the Bombay High Court’s decision in Prakash Krishnavtar Bhardwaj v. ITO, which held that an unsigned notice under Section 148 was invalid and could not confer jurisdiction for reassessment.

After examining the notice and hearing both parties, the Tribunal found that the notice in the present case was also unsigned. Following the Bombay High Court’s ruling, it held that "the unsigned notice issued under section 148 of the Act is invalid. Consequently, the assessment order dated 27.12.2018, passed under section 143(3) read with section 147 of the Act pursuant to such notice, is without jurisdiction and is hereby quashed."
Accordingly, the Tribunal held the entire reassessment proceedings invalid as per the law, and hence, quashed the assessment order dated December 27, 2018, for lack of jurisdiction. As the reassessment was invalidated on this legal ground, the Tribunal did not examine the remaining grounds of appeal. The assessee’s appeal was allowed.
About Author


Saloni Kumari
Content Writer
 StudyCafe
 Delhi, Delhi, India
 2942
My Recent Articles
- ITAT Holds Failure to Issue Draft Assessment Order Under Section 144B Invalidates Assessment Procedure
- TRACES to Soon Permit Cross-Year Challan Corrections Amid New Income Tax Act Transition
- SBI Discloses Customer Data Leak on Dark Web, Identifies 3,897 Records Containing Personally Identifiable Information
- CBDT Exempts Interest on New Development Bank’s Maharajah INR Bonds from TDS
- CBDT Notifies Income-tax (Seventh Amendment) Rules, 2026; Introduces New Form for Tax Exemption Claims
Loading suggestions…


Recent Posts
All Posts
Recent Posts
All Posts