ITAT Quashes Time-Barred Assessment Orders u/s 144C(13) of Income Tax Act, 1961; Favours Assessee:
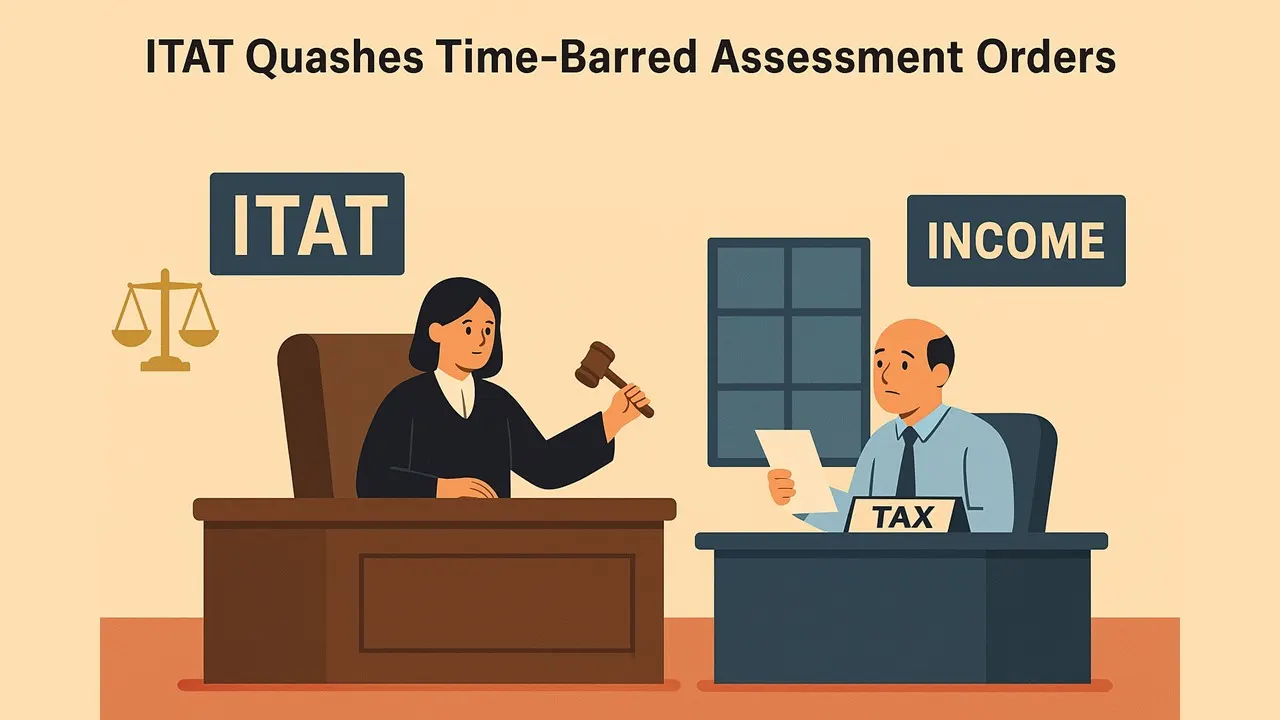
The ITAT set aside Luminous Power’s tax assessments for AY 2017-18 and 2018-19 after finding the orders were issued beyond the statutory deadline under Section 144C(13).
Tribunal Rules Assessment Orders Issued Beyond Deadline Invalid
 Saloni Kumari
 Dec 6, 2025

ITAT Quashes Time-Barred Assessment Orders u/s 144C(13) of Income Tax Act, 1961; Favours Assessee
The ITAT Delhi, in a recent case, ruled in favour of the company, holding that assessment orders for AY 2017-18 and 2018-19 issued after the statutory deadline under Section 144C(13) are not valid as per the law. Since the orders were time-barred, both assessments were set aside.
A company named Luminous Power Technologies Private Ltd. recently approached the Income Tax Appellate Tribunal (ITAT) Delhi, challenging the final assessment orders for Assessment Years (AY) 2017-18 and 2018-19 issued by the Deputy Commissioner of Income Tax, Circle 13(1), New Delhi (tax department). The case was decided on December 05, 2025. The case is related to the assessment years 2017-18 and 2018-19.
For the assessment year 2017-18, the company had declared its income of Rs. 166.06 crore; however, the tax authorities, after scrutinising the return, made an addition to the company's income and declared the total income of the company at Rs. 169.48 crore. Similarly, for the assessment year 2018-19, the company had declared its total income at Rs. 231.92 crore; however, the tax department, after processing the return, declared the total income of the company at Rs. 233.54 crore.
Before the tribunal, the company raised a key issue: that the assessment orders in question were issued beyond the statutory time limit stated under section 144C(13) of the Income Tax Act, 1961. As per this section, the tax department must issue the assessment within the period of one month from the end of the month in which the directions were received, after receiving instructions from the Dispute Resolution Panel (DRP). As per the stated section, the statutory deadline to issue orders was April 30, 2022; however, the tax department issued these orders on May 15 and 18, 2022, respectively.
To support its argument, the company cited several earlier judgments based on the same issue, where the courts had held that assessments passed beyond the statutory deadline are considered invalid. However, the tax department argued that the assessment was valid and was based on merit.
When the tribunal heard the arguments of both sides, it concluded that the company was right and hence ruled that since the assessments were given after the prescribed time, they were not valid and set aside both assessment orders for AY 2017-18 and 2018-19.
About Author


Saloni Kumari
Content Writer
Saloni is a Content Writer with 2+ years of experience at studycafe.in. She writes legal, taxation, and finance related content including GST, Income Tax etc. Skilled in translating complex judicial pronouncements and regulatory developments into clear, and reader-friendly articles. Experienced in covering judgements of ITAT, High Court, GSTAT, and news related to Income Tax, GST, and corporate law. She can be reached at [email protected].
Saloni is a Content Writer with 2+ years of experience at studycafe.in. She writes legal, taxation, and finance related content including GST, Income Tax etc. Skilled in translating complex judicial pronouncements and regulatory developments into clear, and reader-friendly articles. Experienced in covering judgements of ITAT, High Court, GSTAT, and news related to Income Tax, GST, and corporate law. She can be reached at [email protected].
 StudyCafe
 Delhi, Delhi, India
 3036
My Recent Articles
- ITAT Quashes Rs 18.24 Lakh Tax Addition After DVO Values Land at Price Equal to Its Initial Purchase Price
- Mumbai Court Denies Anticipatory Bail to 81-Year-Old CA in Rs 2,575 Crore Foreign Remittance Fraud Case
- Delhi-NCR Couple Under Scanner for Alleged Rs 5.3 Crore Tax Evasion Using Fake Receipts and Fabricated Certificates
- RBI Announces Extension in Supersession of Board of Directors of Abhyudaya Co-operative Bank for Another Year
- ITAT Cancels Section 271D Penalty on Rs 47.54 Lakh Cash Property Sale Over Invocation of Wrong Income Tax Section
Up Next
Loading suggestions…


Recent Posts
All Posts
Tags
Recent Posts
All Posts