No Proceedings Can Be Initiated Under Section 153C for Searches Conducted On Or After April 1, 2021: ITAT:
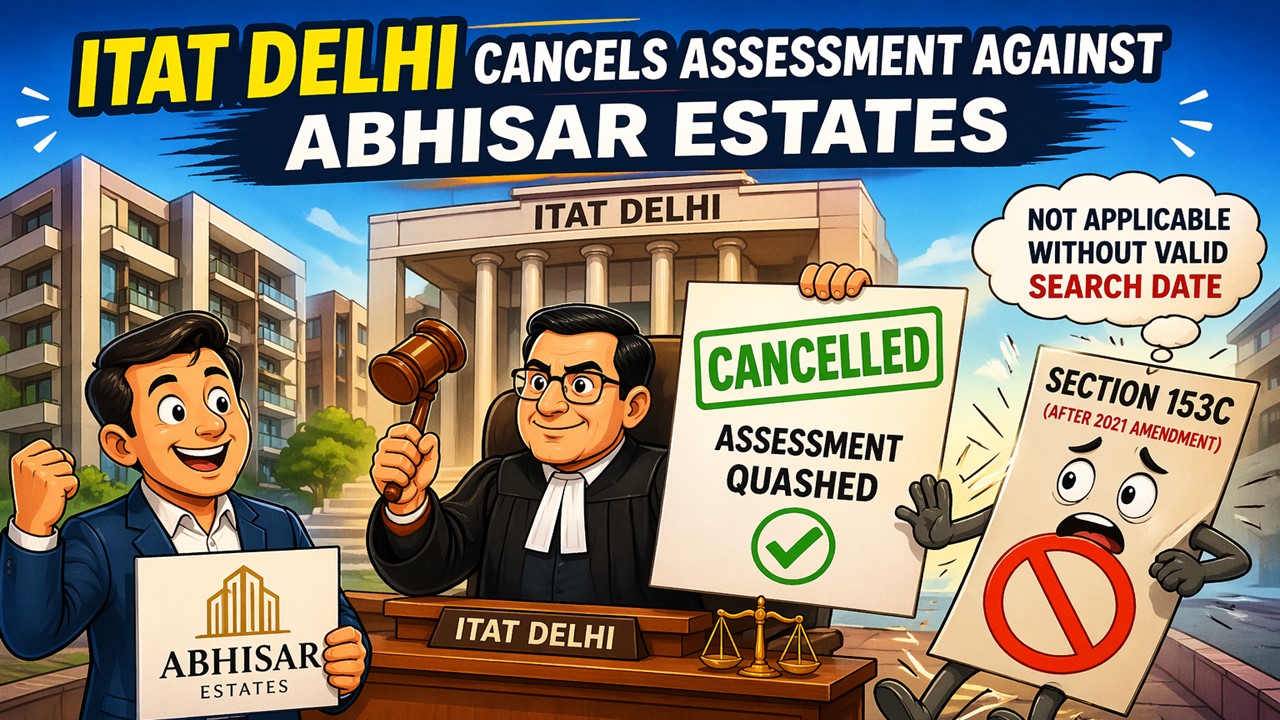
ITAT Delhi cancelled the assessment against Abhisar Estates, holding that Section 153C cannot be applied after the 2021 amendment without a valid search date.
ITAT Delhi Quashes Rs 4.19 Lakh Addition
 Saloni Kumari
 Apr 22, 2026
No Proceedings Can Be Initiated Under Section 153C for Searches Conducted On Or After April 1, 2021: ITAT
The Income Tax Appellate Tribunal (ITAT), Delhi Bench, has given relief to Abhisar Estates Pvt. Ltd. by quashing an assessment made under Section 153C of the Income Tax Act for Assessment Year 2017-18.
The case had begun when the tax authorities initiated a search operation on the Alankit Group on October 18, 2019. The documents found during the search revealed that the assessee had made cash payments amounting to Rs 4.91 lakh during the Assessment Year 2017-18, for which it did not give any explanation. In conclusion, the Assessing Officer (AO) made an addition amounting to Rs 4.19 lakh on the assessee's income under section 69A of the Act.
The aggrieved assessee filed an appeal before the ITAT Delhi, arguing that after the amendment introduced to the Finance Act 2021, Section 153C cannot be pursued for initiating searches linked to dates on or after April 01, 2021. It further explained that since there was no clear record of when the seized documents were received by its AO, the “date of search” should be treated as May 10, 2022, the date when the AO recorded satisfaction.
When the tribunal analysed the case, it endorsed the aforementioned argument. It held that when the exact date of receiving seized material is not available, the date of recording satisfaction must be treated as the date of search. Since May 10, 2022, falls after April 01, 2021, the amended law applies.
After the amendment was introduced to the Finance Act 2021, no proceedings can be initiated under Section 153C for searches conducted on or after 1 April 2021. Therefore, the Tribunal ruled that the notice issued and the assessment made were not valid in law. As a result, the entire assessment was cancelled, and the appeal of the taxpayer was allowed.
About Author

Saloni Kumari
Content Writer
Saloni is a Content Writer with 2+ years of experience at studycafe.in. She writes legal, taxation, and finance related content including GST, Income Tax etc. Skilled in translating complex judicial pronouncements and regulatory developments into clear, and reader-friendly articles. Experienced in covering judgements of ITAT, High Court, GSTAT, and news related to Income Tax, GST, and corporate law. She can be reached at [email protected].
Saloni is a Content Writer with 2+ years of experience at studycafe.in. She writes legal, taxation, and finance related content including GST, Income Tax etc. Skilled in translating complex judicial pronouncements and regulatory developments into clear, and reader-friendly articles. Experienced in covering judgements of ITAT, High Court, GSTAT, and news related to Income Tax, GST, and corporate law. She can be reached at [email protected].
 StudyCafe
 Delhi, Delhi, India
 2770
My Recent Articles
- Gandhidham Tax Consultants Association Urges Finance Ministry to Extend Tax Audit Report Filing Due Date Until October 31
- Centre Notifies Rs 25,000 Monthly Wage Ceiling for Chapter III of Code on Social Security, 2020
- CA Association Seeks Extension of Tax Audit, Forms 10B/10BB and Other Audit-Related Report Deadlines for AY 2026-27
- CBDT Approves IIT Roorkee for Scientific Research Tax Benefits for 5 Years Under Income Tax Act 2025
- Lokayukta Police Arrests Central GST Official, Agent in Rs 8 Lakh Bribery Case
Up Next
Loading suggestions…
Recent Posts
All Posts
Recent Posts
All Posts