Common Approval Under Section 153D for Multiple Years is Invalid: ITAT:
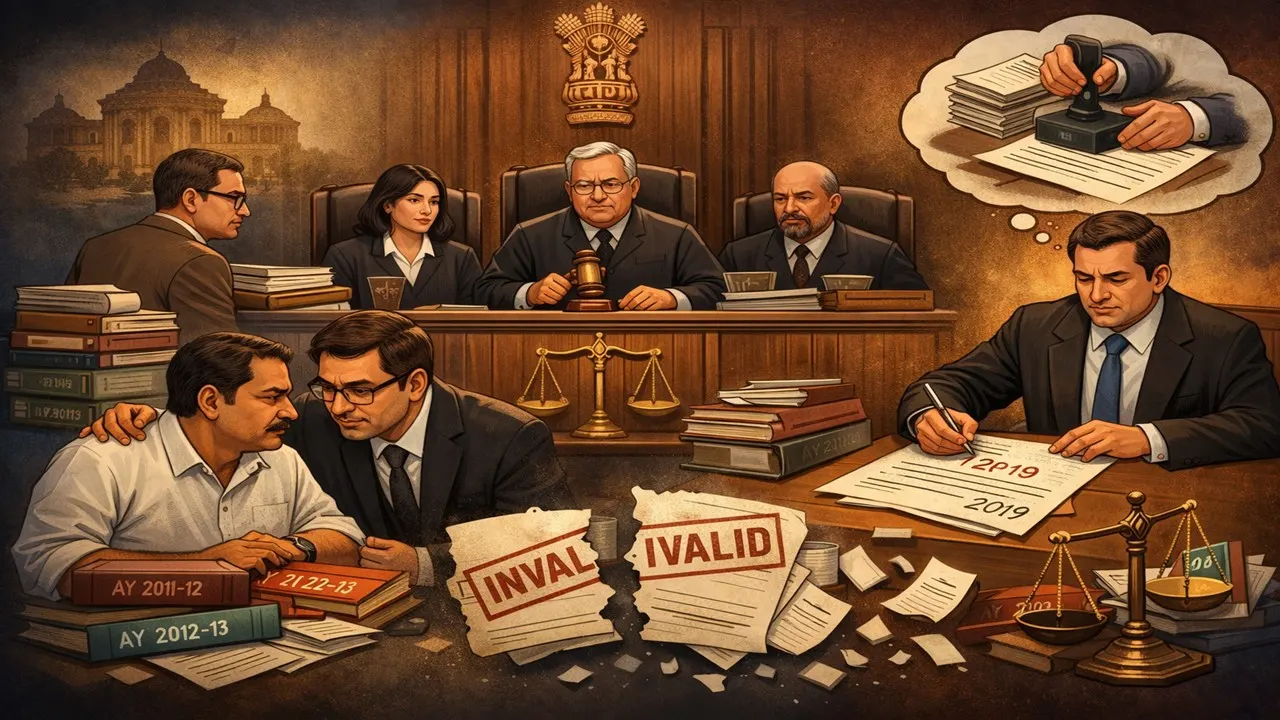
Tribunal held that a single mechanical approval for multiple years violates statutory requirements.
Assessments Quashed as ITAT Finds Non-Application of Mind
 Vanshika verma
 Feb 20, 2026

Common Approval Under Section 153D for Multiple Years is Invalid: ITAT
The ITAT quashed the assessments for AY 2011-12 to 2016-17, holding that a common approval under Section 153D was invalid.
The appeal has been filed by Harakere Seikanta Nagashwarn against ACIT in the ITAT Delhi. These appeals were against the orders passed by the CIT (A).
The CIT(A) had earlier upheld the assessment orders passed by the Assessing Officer under Sections 143(3) and 153A of the Income Tax Act, 1961.
Being aggrieved with this decision, the assessee then filed an appeal before the tribunal. During the hearing, the assessee argued that the assessments were invalid because the approval required under Section 153D of the Act was granted in a mechanical manner and without proper application of mind.
The assessee pointed out that a common approval letter dated December 29, 2019, was used for all the assessment years. According to him, this showed that the approving authority did not independently examine each year’s case.
However, the DR opposed this argument. DR further stated that this issue was not raised earlier before the CIT(A). DR also argued that approval was only a formal requirement and that senior officers were involved throughout the assessment process, so it could not be called mechanical.
After considering all the facts, the tribunal noted that the approval granted under Section 153D was common for all six assessment years. The Tribunal observed that different evidence and documents were relied upon for making additions in different years. Therefore, the law requires separate and year-wise approval after proper examination.
The Tribunal relied on judgements of higher courts, including the decision of the Delhi High Court in the case of PCIT vs. Shiv Kumar Nayyar (2024), which followed the Allahabad High Court decision in Principal Commissioner of Income Tax v. Sapna Gupta (2022). These decisions clearly state that approval under Section 153D must be granted separately for each assessment year.
Based on this, the Tribunal held that the approval granted in this case was improper and not as per law. As a result, the assessment orders passed on the basis of such approval were declared invalid. As a result, the tribunal allowed the assessee's appeals and quashed the assessment order.
About Author

Vanshika verma
Content Writer
Vanshika Verma is a Content Writer with 1+ year of experience at Studycafe.in. A B.Com graduate from Delhi University, She writes articles on Finance, Tax, ICAI, GST, and the latest financial news, with a focus on making complex topics easy for readers and professionals.
Vanshika Verma is a Content Writer with 1+ year of experience at Studycafe.in. A B.Com graduate from Delhi University, She writes articles on Finance, Tax, ICAI, GST, and the latest financial news, with a focus on making complex topics easy for readers and professionals.
 Studycafe
 Delhi, Delhi, India
 2124
My Recent Articles
- eMudhra Announces Exit From Global Digital Certificate Business After Major Security Flaw Raises Internet Safety Concerns
- CBI Court in Ghaziabad Sentences Former Sub Post Master to Three Years in Jail for Misappropriating Rs 15.27 Lakh in Postal Funds
- ITAT Deletes Rs 10 Lakh Penalty Under Black Money Act, Holds Omission of Foreign ESOPs in Schedule FA Was Inadvertent
- GST Council to Use Technology to Curb Fake Invoices and Fraudulent ITC Claims, Shifting Focus from Investigations to Prevention
- SEBI Warns Investors Against Fake WhatsApp Groups Offering Stock Tips, Trading Advice and False Profit Claims
Up Next
Loading suggestions…


Recent Posts
All Posts
Tags
Recent Posts
All Posts