ITAT Grants Major Relief to Small Trader, Limits Tax Liability Using 8% Presumptive Income Rule:
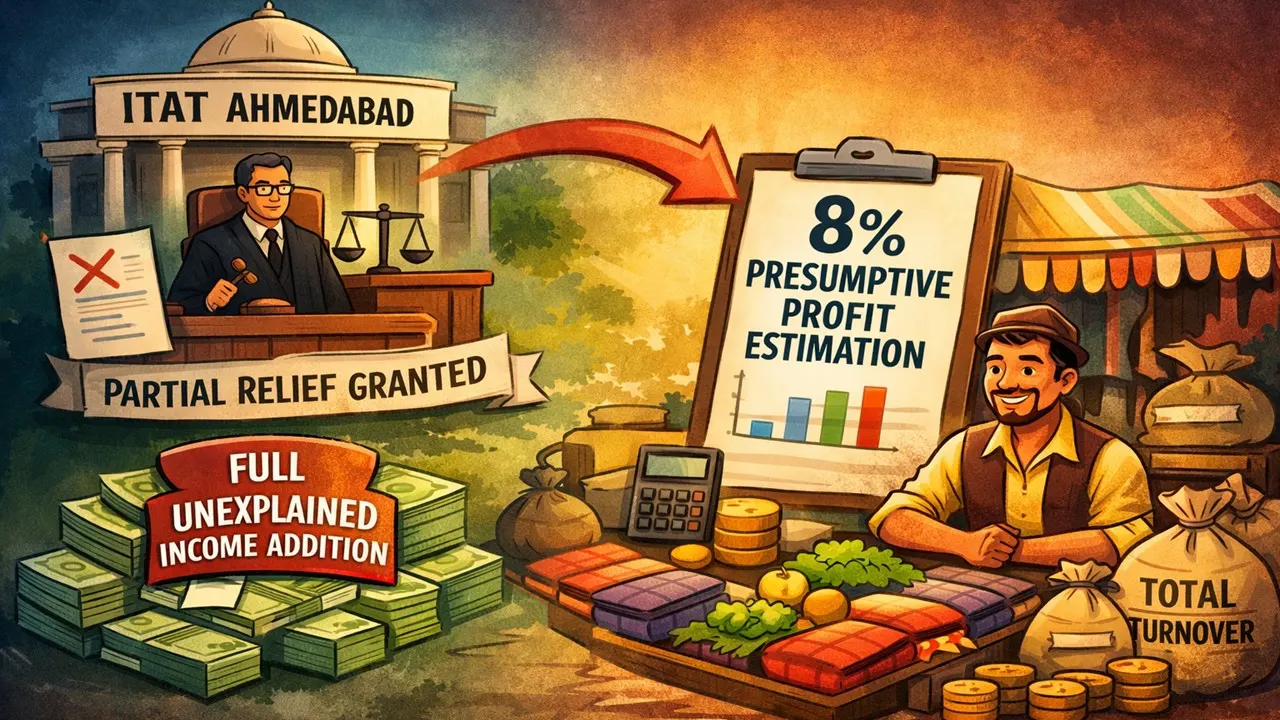
ITAT Ahmedabad granted partial relief to a small trader by replacing a full unexplained income addition with an 8% presumptive profit estimation on total turnover.
ITAT Rejects Full Addition Under Section 69A
 Saloni Kumari
 Mar 27, 2026

ITAT Grants Major Relief to Small Trader, Limits Tax Liability Using 8% Presumptive Income Rule
The ITAT Ahmedabad has announced its final decision on an appeal filed by Rajesh Ramkishan Gupta against the Income Tax Department, challenging an order dated August 08, 2025, passed by the CIT(A), NFAC Delhi. The case belongs to the Assessment Year 2020-21. The impugned order had upheld the additions made by the Assessing Officer (AO) on the grounds of insufficient explanation.
In the present case, the Assessing Officer (AO) had reopened the case of the assessee on the ground that certain documents and materials confiscated during the search conducted in the case of Ambica Fireworks Group of Ashish Jayantilal Khajanji under Section 132 were found linked to the assessee. The AO noted that the assessee was a purchaser from Ambica and had made a cash transaction amounting to Rs 426,100 during the year in consideration.
Considering the same, the AO treated the amount as unexplained income and made an addition of the same under Section 69A. The assessee argued that, being a small retainer operating a seasonal business of firecrackers and kites, he had filed his income tax return (ITR) under Section 44AD and had also furnished all relevant documents during the proceedings. The assessee further claimed that he just could not respond to one of the notices due to a lack of technical knowledge and awareness of online communication. Considering the only non-compliance of not responding to the show cause notice (SCN), the AO made the impugned addition.
When the tribunal analysed the facts of the case, it noted that the assessee was a small trader with a total turnover of Rs 1,120,000. Considering fairness, legal principles, and practical realities, the Tribunal held that instead of treating the entire amount as unexplained income, it would be reasonable to estimate profit. The Tribunal directed the tax authorities to apply an 8% net profit rate on the total turnover, in line with presumptive taxation principles. Consequently, the tribunal partly allowed the appeal by reducing the tax burden.
About Author


Saloni Kumari
Content Writer
Saloni is a Content Writer with 2+ years of experience at studycafe.in. She writes legal, taxation, and finance related content including GST, Income Tax etc. Skilled in translating complex judicial pronouncements and regulatory developments into clear, and reader-friendly articles. Experienced in covering judgements of ITAT, High Court, GSTAT, and news related to Income Tax, GST, and corporate law. She can be reached at [email protected].
Saloni is a Content Writer with 2+ years of experience at studycafe.in. She writes legal, taxation, and finance related content including GST, Income Tax etc. Skilled in translating complex judicial pronouncements and regulatory developments into clear, and reader-friendly articles. Experienced in covering judgements of ITAT, High Court, GSTAT, and news related to Income Tax, GST, and corporate law. She can be reached at [email protected].
 StudyCafe
 Delhi, Delhi, India
 3054
My Recent Articles
- ITAT Deletes Rs 1.70 Crore Additions, Says Purchases Cannot Be Disallowed Without Rejecting Book
- RBI Imposes Rs 9 Lakh Penalty on MobiKwik for Violating PPI and Fraud Reporting Norms
- ITAT Quashes Assessment Order as ACIT Lacked Jurisdiction Without Transfer Order under Section 127
- ITAT Deletes Rs 12.57 Lakh Section 14A Disallowance as Cooperative Bank Earned No Exempt Income
- Credit Cardholders Beware! Eight Settings Every Cardholder Should Review to Curb Fraud Risk
Up Next
Loading suggestions…


Recent Posts
All Posts
Tags
Recent Posts
All Posts