ITAT Quashes Addition Due to Absence of Incriminating Evidence Beyond Third-Party Statements:
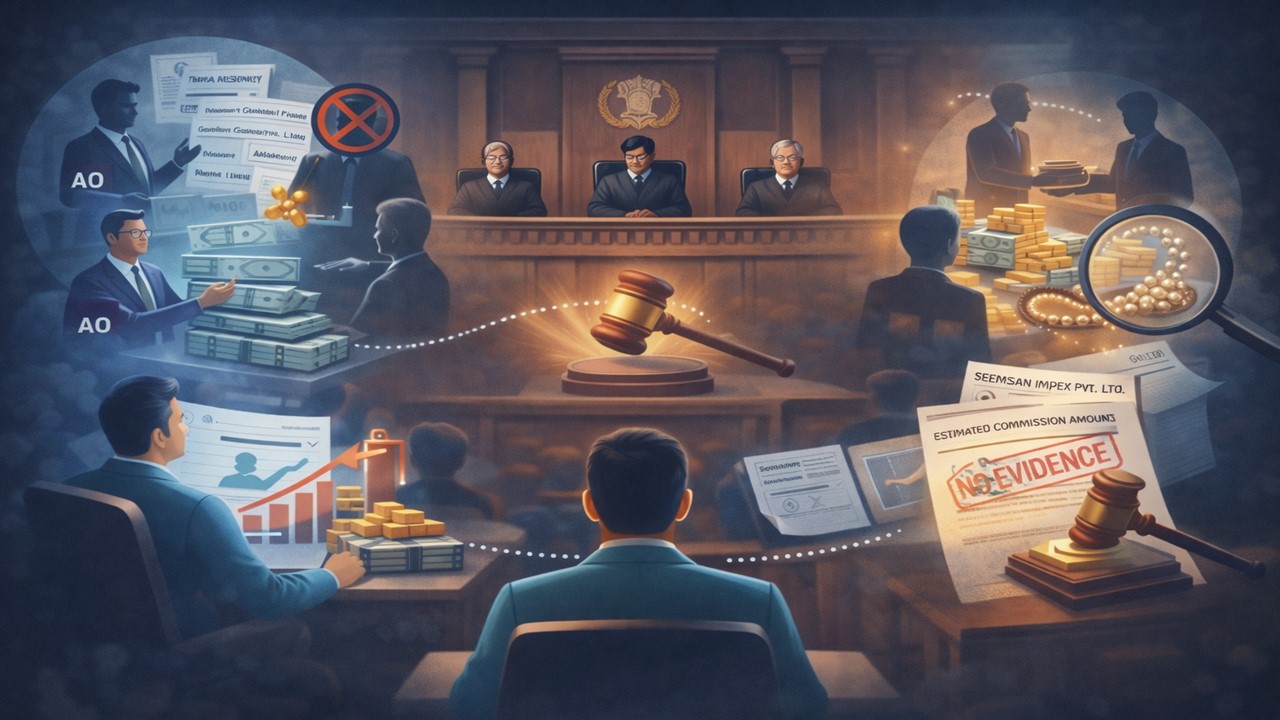
ITAT deleted the addition, holding that tax cannot be imposed merely on third-party statements when no incriminating evidence was found during the search.
Third-Party Claims Cannot Justify Tax Addition, Says ITAT
 Vanshika verma
 Feb 20, 2026

ITAT Quashes Addition Due to Absence of Incriminating Evidence Beyond Third-Party Statements
ITAT Delhi allowed the assessee's appeal and quashed the addition, holding that mere third-party statements without any incriminating evidence found during the search cannot justify assessment.
The present appeal has been filed by Seemsan Impex Pvt. Ltd against DCIT in the ITAT Delhi, challenging the order passed by CIT(A).
The assessee was involved in trading gold and jewellery, etc. Later, the case was selected for scrutiny under Section 143(3) read with Section 153C. During the search, the third party found that multiple shell companies were being operated and managed by the assessee or providing accommodation entries in lieu of commission.
As per the third party, the assessee is alleged to have received credits from fake companies, i.e., M/s Gladiolus Clothing Pvt. Ltd, M/s Heerak Clothing Pvt. Ltd, and M/s Azalea Clothing Pvt. Ltd. Allegedly, these credits were transferred to beneficiaries, and the assessee had earned commission income at 4%, for which an addition is made.
The AO calculated that the assessee handled credit transactions of about Rs. 6,37,18,080 and therefore estimated commission income of Rs. 25,48,723. This amount was added to the assessee’s taxable income.
The assessee then filed an appeal before the CIT(A). However, the CIT(A) agreed with the AO's decision.
Being aggrieved with the CIT(A) decision. The assessee then approached the ITAT. During the hearing, the assessee said the addition was based only on statements recorded during the search. The assessee further added that there was no independent or incriminating evidence against the assessee.
The AR also cited a similar case decided earlier by the Tribunal (Sadhvi Exim Ltd vs DCIT) that had quashed assessments arising from the same search because they were based only on statements without evidence.
However, the DR argued that the statements of the third party clearly showed the accommodation entry business, so the addition was valid.
After considering all the facts, the tribunal noted that no specific incriminating material was found against the assessee during the search. The additions were mainly based on the statement of a third person.
Mere statements or confessions without supporting evidence are not sufficient for making additions under the law. As a result, the tribunal allowed the assessee's appeal and quashed the impugned assessments.
About Author

Vanshika verma
Content Writer
Vanshika Verma is a Content Writer with 1+ year of experience at Studycafe.in. A B.Com graduate from Delhi University, She writes articles on Finance, Tax, ICAI, GST, and the latest financial news, with a focus on making complex topics easy for readers and professionals.
Vanshika Verma is a Content Writer with 1+ year of experience at Studycafe.in. A B.Com graduate from Delhi University, She writes articles on Finance, Tax, ICAI, GST, and the latest financial news, with a focus on making complex topics easy for readers and professionals.
 Studycafe
 Delhi, Delhi, India
 1868
My Recent Articles
- ITAT Holds Repeated Notices Seeking Same Information Cannot Automatically Constitute Separate DefaultsPremium
- Online Betting GST Case: DGGI Hyderabad Conducts Searches at Fintech Firms in Three Cities, Seizes Documents and Digital Records
- ITAT Gives Fresh Opportunity for Section 80G(5) Approval, Holds Wrong Clause Selection in Form 10AB Is Only a Technical ErrorPremium
- ITAT Relief to Vodafone Distributor: Rs 1.50 Lakh Penalty for Non-Audit of Books DeletedPremium
- ITAT Condones 100-Day Delay in Section 80G(5) Appeal, Gives Charitable Trust Fresh Opportunity to Establish Eligibility for ApprovalPremium
Up Next
Loading suggestions…


Recent Posts
All Posts
Tags
Recent Posts
All Posts