ITAT: Renewable Energy Capital Subsidy Not to Reduce Asset Cost for Depreciation in AY 2014-15:
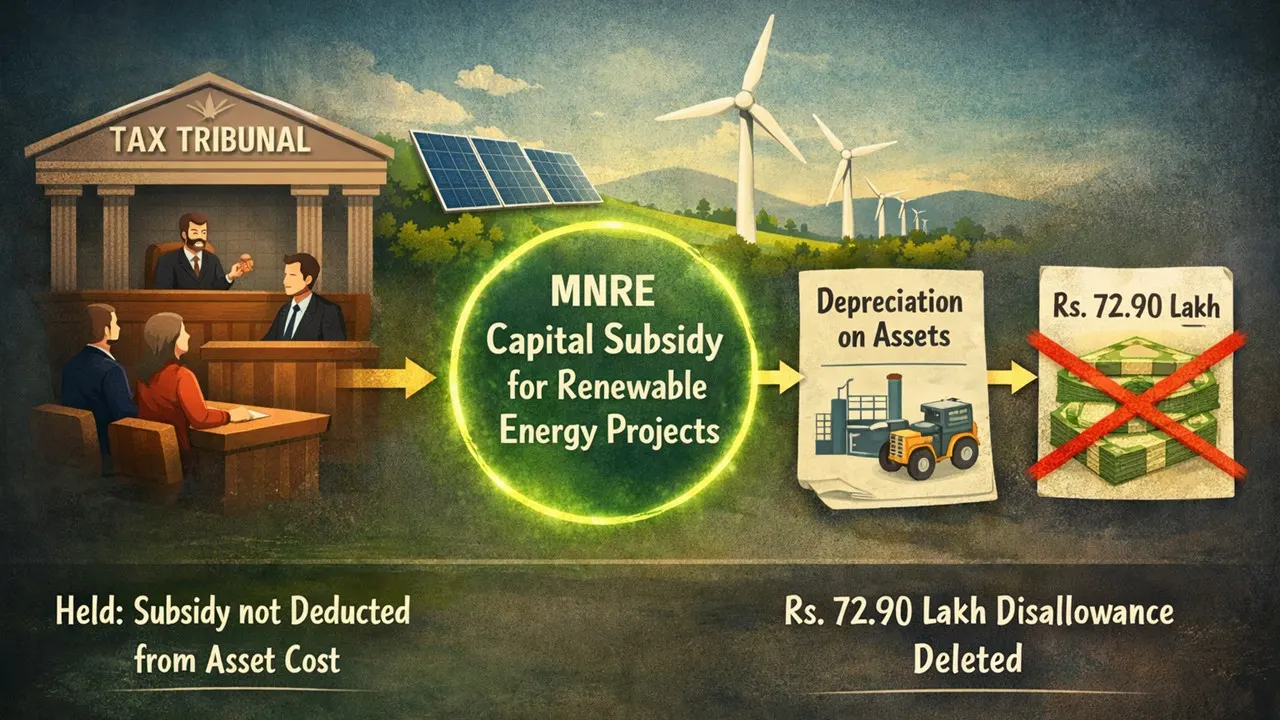
ITAT held that subsidy for promoting renewable energy projects is not deductible from asset cost for depreciation in AY 2014-15, deleting the Rs. 72.90 lakh disallowance.
ITAT Delhi Deletes Rs. 72.90 Lakh Disallowance
 Saloni Kumari
 Dec 25, 2025

ITAT: Renewable Energy Capital Subsidy Not to Reduce Asset Cost for Depreciation in AY 2014-15
ITAT Delhi held that the capital subsidy for promoting renewable energy projects need not reduce the asset cost for depreciation in AY 2014-15. Section 2(24)(xviii) was inapplicable. Depreciation disallowance of Rs. 72.90 lakh was deleted.
Puri Oil Mills Limited has filed the present appeal in the ITAT Delhi, challenging an order dated January 05, 2018, passed by the CIT(A). The main dispute in this case is whether a capital subsidy received by the assessee company should reduce the cost of its fixed assets for depreciation purposes for the Assessment Year (AY) 2014-15.
During the assessment year in consideration, the assessee company filed its income tax return (ITR), declaring the total income of Rs. 5.45 crore. The AO (Assessing Officer) selected the case for scrutiny. It was noted that the assessee had received a capital subsidy worth Rs. 4.86 crore from the Government of India under the Ministry of New and Renewable Energy (MNRE) scheme for establishing Small Hydro Power (SHP) projects in Himachal Pradesh and Haryana. The subsidy was granted to encourage setting up renewable energy projects and was linked to installed capacity (MW), not to the purchase price of specific machinery. The assessee considered this subsidy as a capital receipt and did not reduce the amount from the cost of fixed assets, and hence claimed full depreciation on it.
During scrutiny, AO noted that since the assessee had been given a subsidy on plant and machinery, it should be reduced from the actual cost of assets under Section 43(1). But the assessee did not do so. As a result, AO disallowed the claimed depreciation of Rs. 72.90 lakh (15% of Rs. 4.86 crore). When the case was taken to the CIT(A), the Commissioner of Income Tax (Appeals) [CIT(A)] upheld the disallowance, relying on the same section 2(24)(xviii).
Thereafter, the assessee company approached the ITAT Delhi. After hearing arguments from both sides, the tribunal noted that although the subsidy was released for the promotion of renewable projects, it was not to meet the cost of plant and machinery. It was only a mechanism for the release of incentive, not a payment towards asset cost. To announce the final decision, the tribunal relied on earlier judgements of the Supreme Court and ITAT, including cases titled CIT v. P.J. Chemicals Ltd. and Sasisri Extractions Ltd., all favouring the assessee, ruling that subsidies meant to promote any industrial development should not be deducted from actual cost for the purpose of depreciation.
The Tribunal also held that section 2(24)(xviii) is effective from the AY 2016-17 and cannot be applied to retrospective AYs; hence, it is not applicable to the present case either. In conclusion, the Tribunal held the Assessing Officer wrong for disallowing depreciation of Rs. 72.90 lakh. Allowed all the grounds raised by the assessee and allowed the appeal in full.
About Author


Saloni Kumari
Content Writer
Saloni is a Content Writer with 2+ years of experience at studycafe.in. She writes legal, taxation, and finance related content including GST, Income Tax etc. Skilled in translating complex judicial pronouncements and regulatory developments into clear, and reader-friendly articles. Experienced in covering judgements of ITAT, High Court, GSTAT, and news related to Income Tax, GST, and corporate law. She can be reached at [email protected].
Saloni is a Content Writer with 2+ years of experience at studycafe.in. She writes legal, taxation, and finance related content including GST, Income Tax etc. Skilled in translating complex judicial pronouncements and regulatory developments into clear, and reader-friendly articles. Experienced in covering judgements of ITAT, High Court, GSTAT, and news related to Income Tax, GST, and corporate law. She can be reached at [email protected].
 StudyCafe
 Delhi, Delhi, India
 3054
My Recent Articles
- ITAT Deletes Rs 1.70 Crore Additions, Says Purchases Cannot Be Disallowed Without Rejecting Book
- RBI Imposes Rs 9 Lakh Penalty on MobiKwik for Violating PPI and Fraud Reporting Norms
- ITAT Quashes Assessment Order as ACIT Lacked Jurisdiction Without Transfer Order under Section 127
- ITAT Deletes Rs 12.57 Lakh Section 14A Disallowance as Cooperative Bank Earned No Exempt Income
- Credit Cardholders Beware! Eight Settings Every Cardholder Should Review to Curb Fraud Risk
Up Next
Loading suggestions…


Recent Posts
All Posts
Tags
Recent Posts
All Posts