Fujiyama Power Systems (UTL Solar) Faces Rs 13.97 Crore Customs Duty Demand Over Alleged Misclassification of Imports:
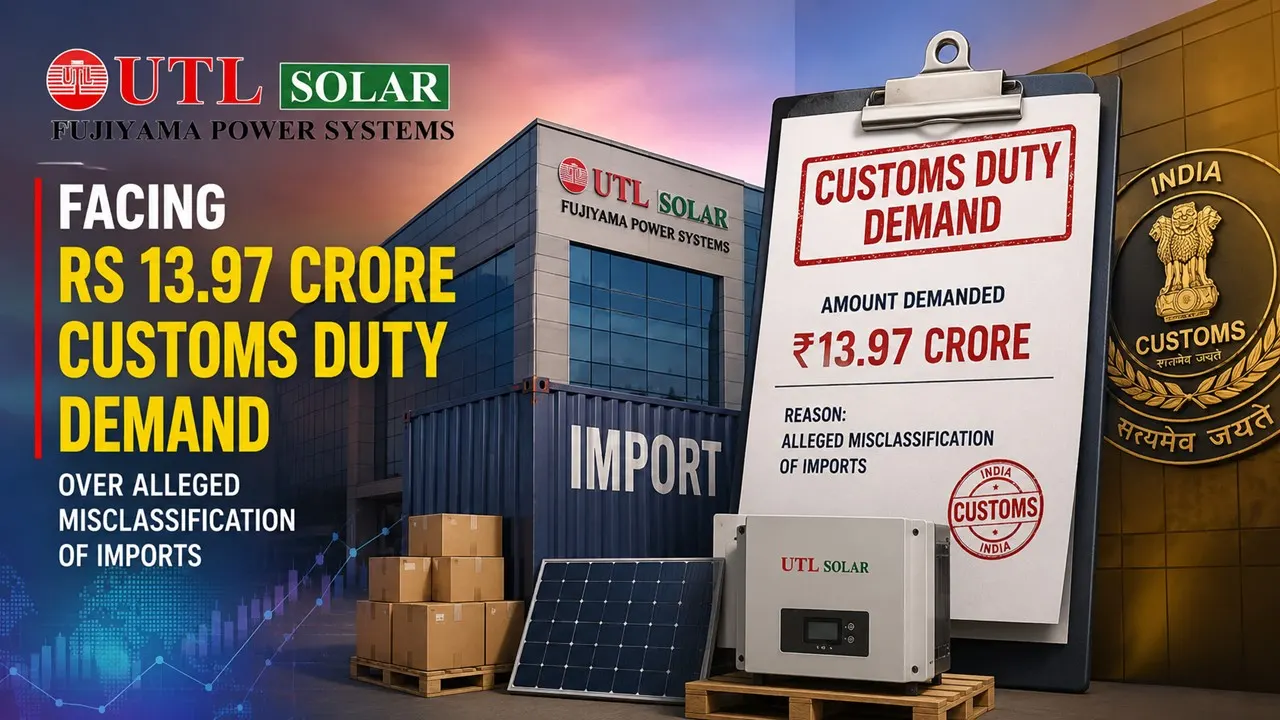
Fujiyama Power Systems (UTL Solar) has received a Customs SCN proposing a Rs 13.97 crore duty demand over the alleged misclassification of imported goods.
Company Planning to Challenge Demand Before Relevant Appellate Authority
 Saloni Kumari
 Jun 19, 2026

Fujiyama Power Systems (UTL Solar) Faces Rs 13.97 Crore Customs Duty Demand Over Alleged Misclassification of Imports
Fujiyama Power Systems Limited (UTL Solar) has informed the stock exchange (National Stock Exchange Limited and Bombay Stock Exchange Limited) about the receipt of a Show Cause Notice (SCN) No. 01/Commr/Noida/Cus/2026-27, dated June 17, 2026, from the Office of the Assistant Commissioner of Customs, Noida Customs Commissionerate, under Section 28(4) of the Customs Act, 1962.
As per the disclosure, the company had received the notice on June 17, 2026, at 18:49 hrs, meaning after office working hours, at its official e-mail ID. The notice has proposed recovery of differential duty of Rs 13.96 crore, alleging the company for misreporting imported goods (declared Customs tariff item: 85049090) and thereafter claiming eligible exemption under Notification No. 57/2017-Customs, dated June 30, 2017.
According to the concerned authorities, the goods in question imported during the financial year 2024-25 (assessment year 2025-26) and before that period need to be reassessed under Customs Tariff Item 85044090 and charged duties accordingly.
The company is asked to show cause why the following actions should not be taken against it:
- Rejection of the declared classification of the imported goods and re-classification of the same under CTI 85044090, and denial of the benefit of exemption notifications and re-assessment;
- Confiscation of the imported goods in question under the provisions of Section 111(m) of the Customs Act, 1962;
- Recovery of differential Customs duty of about Rs 13.97 Crores under Section 28(4) of the Customs Act, 1962, along with the imposition of interest under Section 28AA, ibid. and penalties.
About Author


Saloni Kumari
Content Writer
Saloni is a Content Writer with 2+ years of experience at studycafe.in. She writes legal, taxation, and finance related content including GST, Income Tax etc. Skilled in translating complex judicial pronouncements and regulatory developments into clear, and reader-friendly articles. Experienced in covering judgements of ITAT, High Court, GSTAT, and news related to Income Tax, GST, and corporate law. She can be reached at [email protected].
Saloni is a Content Writer with 2+ years of experience at studycafe.in. She writes legal, taxation, and finance related content including GST, Income Tax etc. Skilled in translating complex judicial pronouncements and regulatory developments into clear, and reader-friendly articles. Experienced in covering judgements of ITAT, High Court, GSTAT, and news related to Income Tax, GST, and corporate law. She can be reached at [email protected].
 StudyCafe
 Delhi, Delhi, India
 3059
My Recent Articles
- Man Earning Rs 15,000 Monthly Shocked as Rs 350 Crore Transactions Made in His Name Using Fake Documents
- Cyber Criminals Defraud 72-Year-Old Retired Bank Employee of Rs 1.42 Crore Through Digital Arrest Scam
- ITAT Deletes Rs 1.5 Crore Addition, Says Alleged Accommodation Entry Cannot Automatically Be Treated as Taxpayer's Income
- Mahadev Betting App Case: CBI Conducts Searches at 33 Locations Across 6 States, Dismantles Live Panels
- Kerala Businessman Loses Rs 1.45 Crore in Investment Scam Using AI-Generated Video Featuring Finance Minister
Up Next
Loading suggestions…


Recent Posts
All Posts
Recent Posts
All Posts