CBDT Notifies Approval of Sikshya O Anusandhan for Scientific Research Under Section 35:
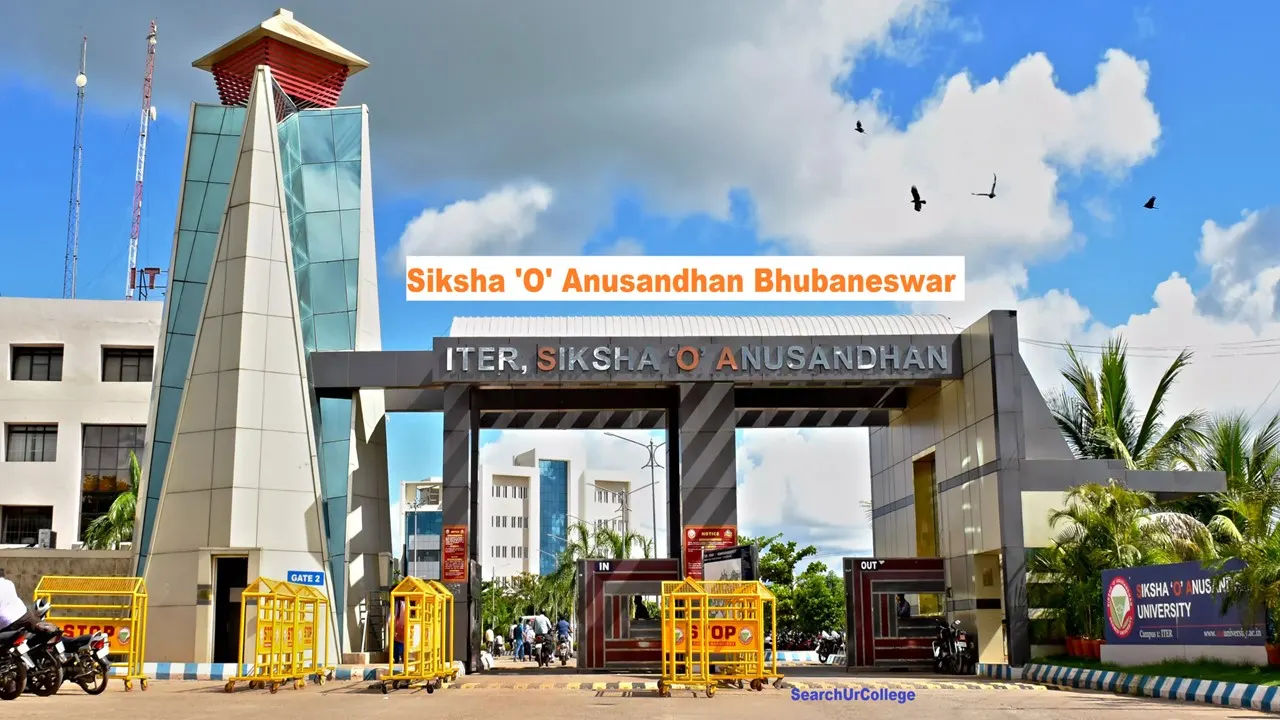
CBDT approves Sikshya O Anusandhan for tax benefits on scientific research under Section 35 of the Income Tax Act
CBDT Grants Approval of Sikshya O Anusandhan for Tax Benefits on Scientific Research
 Vanshika verma
 Jan 29, 2026

CBDT Notifies Approval of Sikshya O Anusandhan for Scientific Research Under Section 35
The Central Board of Direct Taxes (CBDT) under the Ministry of Finance recently shared a notification (No. 14/2026) on January 27, 2026, regarding approving the Sikshya O Anusandhan for scientific research.
The Central government using its power given by clause (ii) of sub-section (1) of section 35 of the Income tax Act, 1961 (43), read with Rules 5C and 5E of the Income-tax Rules, 1962 approves 'Sikshya O Anusandhan' (PAN: AABTS1525R), Bhubaneswar, Odisha for 'Scientific Research' under the category of 'University, college or other institution'.
This notification is applicable for the assessment years 2026-27 to 2030-31, subject to the conditions below:
1. Sikshya O Anusandhan, Bhubaneswar, Odisha, will follow the conditions mentioned in Rule 5E of the Income-tax Rules, 1962.
2. Sikshya O Anusandhan, Bhubaneswar, Odisha, must prepare a statement under Section 35(1A) of the Act for every financial year in Form No. 10BD. This statement must be submitted to the prescribed Income-tax authority or an authorised person in the prescribed format and manner. It should include all required details and must be filed on or before 31st May following the financial year in which the donation was received, as per Rule 18AB of the Income-tax Rules, 1962.
Such a university, college, or other institution is also allowed to submit a correction statement to the concerned authority if they need to fix any mistake or make changes. They can use this to add new information, remove incorrect details, or update previously submitted information under section 35(1A) of the Act.
3. Sikshya O Anusandhan, Bhubaneswar, Odisha, will give the donor a certificate in Form 10BE specifying the amount donated. This certificate will include all required details and will be provided within the time limit set under Rule 18AB of the Income-tax Rules, 1962.
About Author

Vanshika verma
Content Writer
Vanshika Verma is a Content Writer with 1+ year of experience at Studycafe.in. A B.Com graduate from Delhi University, She writes articles on Finance, Tax, ICAI, GST, and the latest financial news, with a focus on making complex topics easy for readers and professionals.
Vanshika Verma is a Content Writer with 1+ year of experience at Studycafe.in. A B.Com graduate from Delhi University, She writes articles on Finance, Tax, ICAI, GST, and the latest financial news, with a focus on making complex topics easy for readers and professionals.
 Studycafe
 Delhi, Delhi, India
 2187
My Recent Articles
- What Can You Trade During Muhurat Trading 2026? Stocks, ETFs, F&O and MTF Explained
- Bharti Airtel Receives Rs 1.07 Lakh Penalty Notice From DoT Maharashtra Over Alleged Subscriber Verification Violations
- Rashi Peripherals Faces Rs 2.15 Crore Customs Duty and Penalty Demand Over Alleged Misclassification of Imported Goods, Considers CESTAT Appeal
- High-Profile Birthday Party at Rajkot's Saraza Hotel Raided by LCB; Prominent Industrialists and Business Leaders Under Scanner
- CBI Academy Hosts One-Week International ITEC Training Programme to Enhance Skills in Anti-Corruption Investigation and Recovery of Illicit Assets
Up Next
Loading suggestions…


Recent Posts
All Posts
Recent Posts
All Posts