GST Portal Opens GSTR-9 and GSTR-9C Filing for FY 2025-26: Check Due Date and Key Points:
The GST department has officially opened the GSTR-9 and GSTR-9C forms for filing annual returns on the portal for Financial Year 2025-26.
Who Must File GSTR-9 and GSTR-9C?
 Saloni Kumari
 Oct 12, 2026

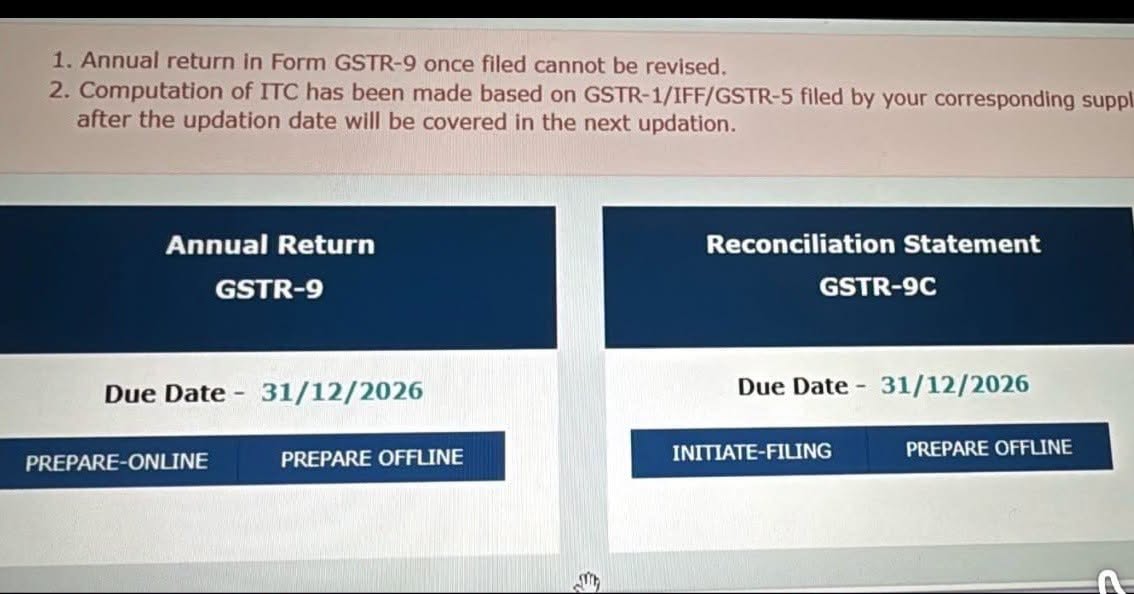
The GST department has officially opened the GSTR-9 and GSTR-9C forms for filing annual returns on the portal for Financial Year 2025-26 (Assessment Year 2026-27). The due date to furnish the return is December 31, 2026.
Key Points to Keep in Mind

The following are some key points filers should keep in mind before completing the filing process:
No revision can be made after completing the GSTR-9 filing process. Reconcile your books with the returns first.
Taxpayers should first claim their pending ITC (Input Tax Credit). ITC for the FY 2025-26 can be claimed upto November 30, 2026, or the date of filing the relevant annual return, whichever is earlier. Taxpayers are recommended to avail their pending ITC first before commencing the return filing process.

Match your books with GSTR-1, GSTR-3B, GSTR-2B and the relevant ITC records. Investigate differences before finalising the return.
Always check your HSN and rate-wise data carefully. This year covers two rate structures, effective from September 22, 2025.
The GSTR-9 filing requires more accuracy than speed, as once the return is filed, no changes can be made thereafter. Complete the reconciliation, claim eligible ITC and verify the rate-wise data before you submit. “There is no second chance with GSTR-9, so get it right the first time.”
Who is Eligible to File GSTR-9 Return?
The following are the categories of taxpayers who need to file GSTR-9:
Turnover up to Rs 2 crore: Exempt from filing GSTR-9 under Notification No. 15/2025-Central Tax dated 17 September 2025.
Turnover above Rs 2 crore and up to Rs 5 crore: GSTR-9 is generally mandatory; GSTR-9C is not required.
Turnover above Rs 5 crore: Both GSTR-9 and self-certified GSTR-9C are required.
Late Fee Applicable When Return Is Not Furnished Promptly
The prescribed annual-return late fee depends on turnover:
A late fee of Rs 50 per day applies in case turnover is upto Rs 5 crore.
A late fee of Rs 100 per day applies in case turnover is between Rs 5 crore and Rs 20 crore.
A late fee of Rs 200 per day applies in case turnover is above Rs 20 crore.
About Author

Saloni Kumari
Content Writer
 StudyCafe
 Delhi, Delhi, India
 2890
My Recent Articles
- ITAT Sets Aside Rejection of Charitable Trust’s Section 12AB Registration Application, Remands Case to CIT(E) for Fresh Consideration
- Can Same-Sex Partners Claim Tax Exemption on Gifts as Spouses? Karnataka High Court to Examine
- ITAT Remits Section 80G Renewal Application to CIT(E) for Fresh Consideration in Light of CBDT Circular
- Dreamfolks Services Faces Rs 1.58 Crore IGST Demand Over ITC Availment on Invoices Issued by GST-Cancelled Supplier
- ITAT Restores Taxpayer's Appeal In Interest of Natural Justice After CIT(A)'s Failure to Decide Appeal on Merits
Loading suggestions…


Recent Posts
All Posts
Recent Posts
All Posts