High Court Grants Section 80P Exemption despite Belated ITR Filing:
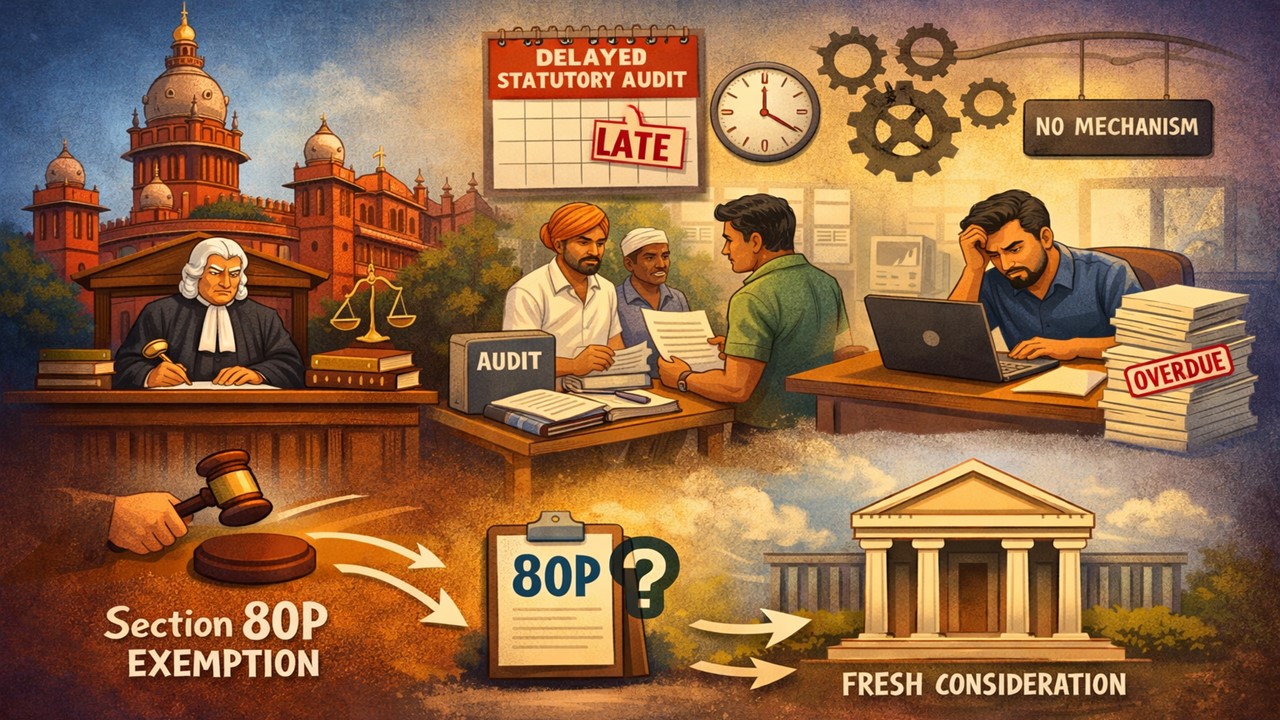
The HC holds that cooperative societies generally face difficulty in filing returns timely because of the belated approval of statutory audits and the absence of an adequate mechanism.
Section 80P Exemption Case Remanded for Fresh Consideration
 Saloni Kumari
 Apr 10, 2026

High Court Grants Section 80P Exemption despite Belated ITR Filing
The Madras High Court grants relief to Irukkandurai Primary Agriculture Cooperative Credit Society, holding that cooperative societies generally face difficulty in filing returns timely because of the belated approval of statutory audits and the absence of an adequate mechanism.
The tax authorities had rejected the society's tax exemption claim, made under Section 80P of the Income Tax Act, 1961, because it had not furnished its ITR within the statutory time limit prescribed under Section 80-AC.
During the personal hearing before the High Court, the petitioner claimed that the delay was not intentional, and additionally, it was also willing to file an application seeking condonation of the delay under Section 119(2)(b) of the Act. However, the tax authorities claimed that the society had neither filed an application for condonation of delay nor furnished any appeal challenging the denial of its Section 80P exemption claim.
When the court analysed the case, it noted that cooperative societies often face practical difficulties like belated approval of statutory audits and the absence of an adequate mechanism, which ultimately leads to delays in filing their returns. The court highlighted that such delays are not always due to the intention of tax evasion but sometimes due to procedural challenges.
Considering all the challenges faced by society, the court decided to grant it another chance of relief. The society has been directed to file an application seeking condonation of delay within two weeks with the Chief Commissioner, explaining the detailed reasons behind the delay. Thereafter, the Chief Commissioner must decide on the application within three months. Thereafter, the society is directed to file an appeal before the ITAT along with the condonation of the delay application. The Tribunal has been asked to consider the Chief Commissioner’s decision while deciding the appeal.
About Author


Saloni Kumari
Content Writer
Saloni is a Content Writer with 2+ years of experience at studycafe.in. She writes legal, taxation, and finance related content including GST, Income Tax etc. Skilled in translating complex judicial pronouncements and regulatory developments into clear, and reader-friendly articles. Experienced in covering judgements of ITAT, High Court, GSTAT, and news related to Income Tax, GST, and corporate law. She can be reached at [email protected].
Saloni is a Content Writer with 2+ years of experience at studycafe.in. She writes legal, taxation, and finance related content including GST, Income Tax etc. Skilled in translating complex judicial pronouncements and regulatory developments into clear, and reader-friendly articles. Experienced in covering judgements of ITAT, High Court, GSTAT, and news related to Income Tax, GST, and corporate law. She can be reached at [email protected].
 StudyCafe
 Delhi, Delhi, India
 2847
My Recent Articles
- NU Vista Receives Rs 24.98 Crore Tax Demand Show Cause Notice for FY 2022-23 Over Yield Calculation and Moisture Loss
- Ramco Systems’ Philippines Subsidiary Settles Tax Demand at PHP 3 Mn Against Original PHP 72.40 Mn Claim
- Mahindra Holidays Receives GST Show Cause Notice Proposing Rs 36.29 Crore Demand for FY 2022-23
- Govt Extends RoDTEP Scheme for Exporters Till Dec 31, 2026, Existing Rates and Value Caps Remain Unchanged
- ICAI Proposes Rs 5 Crore Government Consultancy Tenders Reservation for Firms with Lower Net Worth
Up Next
Loading suggestions…


Recent Posts
All Posts
Recent Posts
All Posts