ITAT Allows Section 80G Renewal Application Where Delay Was Due to Late Grant of Approval:
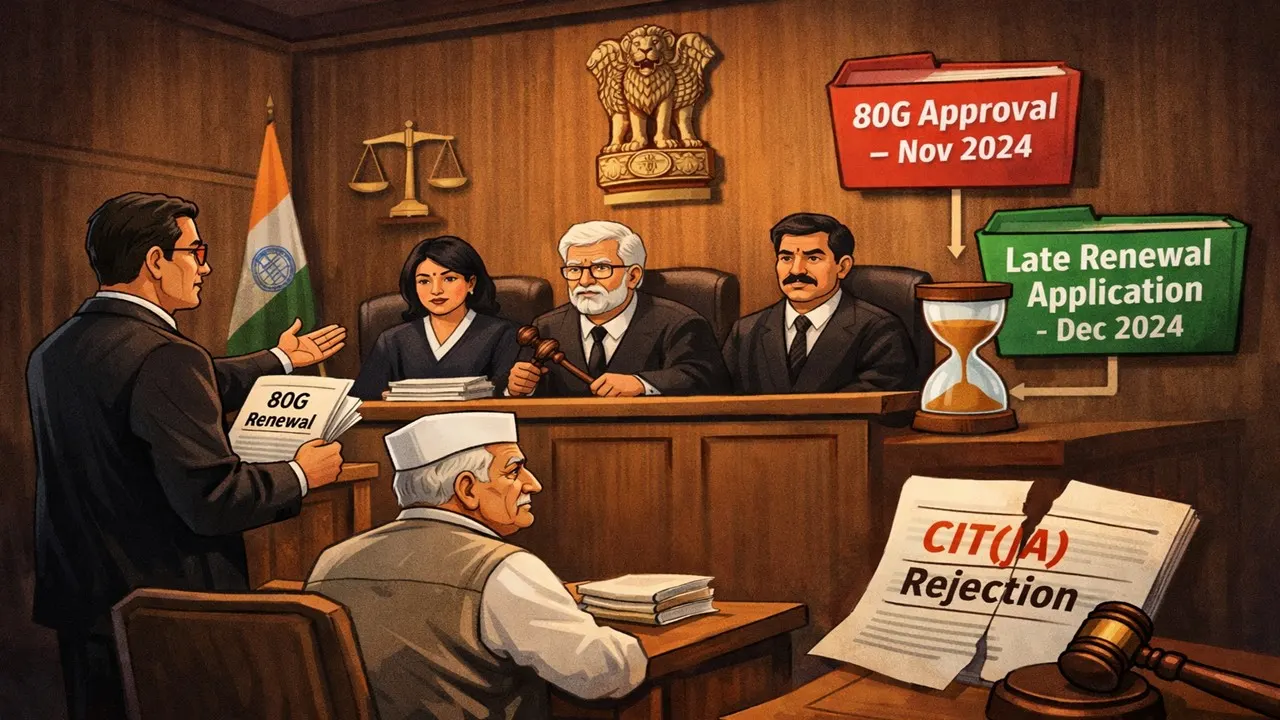
ITAT condoned the delay in Section 80G renewal and allowed the appeal, holding that the late filing caused by the delayed grant of approval was a genuine and valid reason.
ITAT Favours Foundation, Sets Aside Rejection of 80G Renewal
 Saloni Kumari
 Dec 21, 2025

ITAT Allows Section 80G Renewal Application Where Delay Was Due to Late Grant of Approval
ITAT says assessees must apply for Section 80G renewal at least six months prior to the expiry date of the regular Section 80G approval. Delay does not permit renewal, unless it is genuine.
Scon Pro Foundation filed the current appeal before the ITAT Pune, challenging an order passed by the CIT(Exemption) Pune on June 04, 2025. The order rejected the assessee's registration application filed under Section 80G(5) of the Income Tax Act on the grounds that the application was filed after the statutory time limit.
The trust earlier had approval under Section 80G, valid up to March 31, 2025. The rule says one should apply for renewal at least six months prior to the date of expiry. Hence, in the present case, the trust should have applied for the same before September 30, 2024. However, the trust applied for renewal of registration on December 31, 2024, which is about 90 days late from the legal deadline. In conclusion, CIT(Exemption) rejected the assessee's application on the grounds that the application was filed beyond the time limit allowed under the provisions of section 80G subsection (5) of the IT Act.
The assessee thereafter filed an appeal before ITAT Pune, where the assessee claimed that its regular 80G approval itself was granted very late, on November 21, 2024. Hence, practically, it was impossible to apply for renewal prior to September 30, 2024; hence, the tribunal was requested to ignore the delay and restore the application.
The tribunal noted that the assessee was right; its initial 80G approval was indeed received by it on November 21, 2024, which is very late. Hence, relying on earlier judgements based on the same issue condoned the delay and set aside the order of CIT(Exemption). Also, sent the matter back to the CIT(Exemption) for fresh consideration. In the end, allows the appeal.
About Author


Saloni Kumari
Content Writer
Saloni is a Content Writer with 2+ years of experience at studycafe.in. She writes legal, taxation, and finance related content including GST, Income Tax etc. Skilled in translating complex judicial pronouncements and regulatory developments into clear, and reader-friendly articles. Experienced in covering judgements of ITAT, High Court, GSTAT, and news related to Income Tax, GST, and corporate law. She can be reached at [email protected].
Saloni is a Content Writer with 2+ years of experience at studycafe.in. She writes legal, taxation, and finance related content including GST, Income Tax etc. Skilled in translating complex judicial pronouncements and regulatory developments into clear, and reader-friendly articles. Experienced in covering judgements of ITAT, High Court, GSTAT, and news related to Income Tax, GST, and corporate law. She can be reached at [email protected].
 StudyCafe
 Delhi, Delhi, India
 2942
My Recent Articles
- ITAT Holds Failure to Issue Draft Assessment Order Under Section 144B Invalidates Assessment Procedure
- TRACES to Soon Permit Cross-Year Challan Corrections Amid New Income Tax Act Transition
- SBI Discloses Customer Data Leak on Dark Web, Identifies 3,897 Records Containing Personally Identifiable Information
- CBDT Exempts Interest on New Development Bank’s Maharajah INR Bonds from TDS
- CBDT Notifies Income-tax (Seventh Amendment) Rules, 2026; Introduces New Form for Tax Exemption Claims
Up Next
Loading suggestions…


Recent Posts
All Posts
Tags
Recent Posts
All Posts