ITAT Flags Functional Mismatch in TP Comparables, Sends Matter Back:
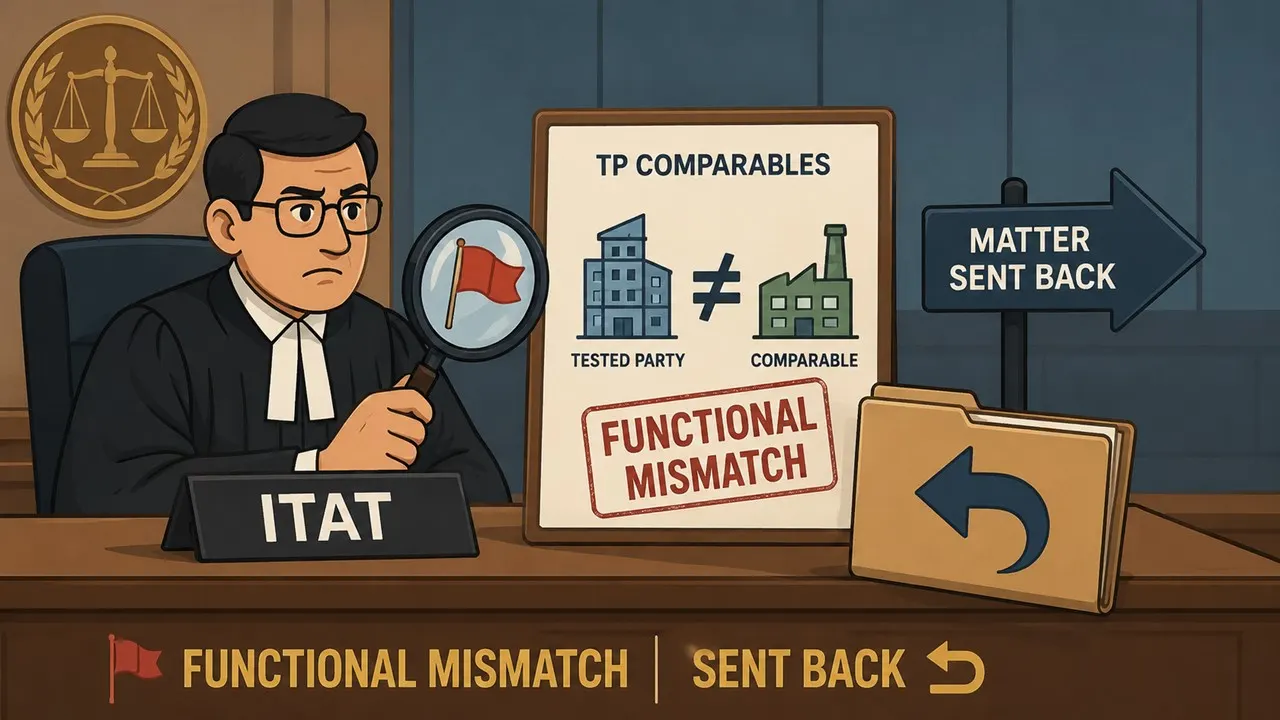
Tribunal remanded the transfer pricing dispute after finding key comparables functionally different from the assessee’s business.
ITAT Flags Faulty TP Comparables
 Vanshika verma
 May 28, 2026

ITAT Flags Functional Mismatch in TP Comparables, Sends Matter Back
The Delhi bench of the Income Tax Appellate Tribunal (ITAT) has sent back a transfer pricing dispute involving Mitsui Prime Advanced Composites India Private Limited to the Assessing Officer (AO) for fresh review.
The case relates to Assessment Year 2016-17. The company had filed its income tax return showing "Nil" income. The case was later taken up by the tax department for detailed scrutiny on various issues, including foreign transactions, business losses, share capital, foreign remittances and transfer pricing compliance.
The company is engaged in the business of manufacturing and trading in polypropylene and polyolefin compounds. The issue was referred to the Transfer Pricing Officer (TPO) on account of international transactions with its Associated Enterprises (AEs).
The TPO proposed a transfer pricing adjustment to the tune of Rs. 1,99,32,839. Later, after directions from the Dispute Resolution Panel (DRP), the AO finally made an adjustment of Rs. 1,81,74,359.
The company challenged the order before the ITAT, arguing that the tax department wrongly increased its income and even added the transfer pricing adjustment twice. According to the assessee, this resulted in its total income being wrongly assessed at Rs 3,81,07,198 instead of Nil income.
The assessee also argued that the AO failed to properly allow the set-off of carried forward losses and unabsorbed depreciation amounting to more than Rs 55,48,52,977.
On the transfer pricing issue, the company claimed that several companies selected by the TPO as comparables were not actually similar to its business activities. It argued that these companies manufactured very different products and had different business models, raw material costs, risks, and depreciation methods.
The Tribunal examined three comparables selected by the TPO:
- Zenith Fibres Ltd: engaged in manufacturing PP staple fibre and yarn, which the Tribunal noted was different from the assessee’s business.
- Resins & Plastics Ltd: engaged in manufacturing several types of resins and chemicals, unlike the assessee’s polypropylene compounds business.
- NOCIL Limited: engaged in manufacturing rubber chemicals, again, functionally different from the assessee.
- Sreechem Resins Ltd.
- Pankaj Polymers Ltd.
- Axel Polymers Ltd.
- Kingfa Science & Technology (India) Ltd.
- Machino Polymers Ltd.

About Author

Vanshika verma
Content Writer
Vanshika Verma is a Content Writer with 1+ year of experience at Studycafe.in. A B.Com graduate from Delhi University, She writes articles on Finance, Tax, ICAI, GST, and the latest financial news, with a focus on making complex topics easy for readers and professionals.
Vanshika Verma is a Content Writer with 1+ year of experience at Studycafe.in. A B.Com graduate from Delhi University, She writes articles on Finance, Tax, ICAI, GST, and the latest financial news, with a focus on making complex topics easy for readers and professionals.
 Studycafe
 Delhi, Delhi, India
 2150
My Recent Articles
- Former National Archives Archivist Sentenced to Three Years in Jail by Ahmedabad CBI Court for Accepting Rs 15,000 Bribe
- B.Tech Biotechnology in Delhi NCR: Exploring The Curriculum, College Facilities and Career Prospects
- CBI Arrests Income Tax Inspector in Mumbai for Allegedly Accepting Rs 15 Lakh Bribe to Close Benami Property Case
- Centre Amends Customs Duty Exemptions for Defence Equipment and Spare Parts
- Government Amends GST Rate Notification Under Section 11(1) of the CGST Act, 2017, to Update The Definition of Nominated Agency
Up Next
Loading suggestions…


Recent Posts
All Posts
Tags
Recent Posts
All Posts