ITAT Quashes Rectification Order, Restores Section 11 Exemption Over Late Form 10B Filing:
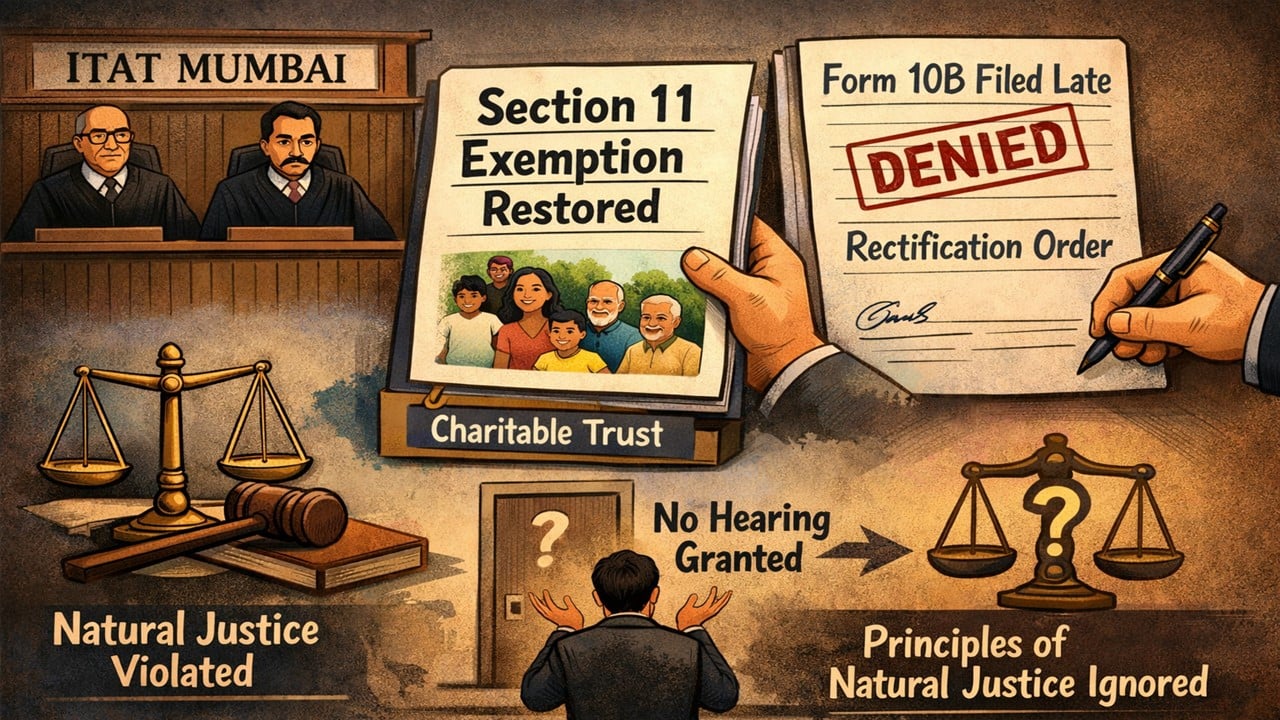
ITAT restored Section 11 exemption, holding that denial based on late Form 10B filing without granting a hearing was invalid and violated principles of natural justice.
ITAT Cites Violation to Principles of Natural Justice
 Saloni Kumari
 Mar 29, 2026

ITAT Quashes Rectification Order, Restores Section 11 Exemption Over Late Form 10B Filing
The ITAT Mumbai set aside a rectification order passed denying the Section 11 exemption because Form 10B was filed late, holding that the company was awarded a proper opportunity of hearing before issuing the order.
The appeal was filed by a charitable trust named Tehmina K. Katrak Charitable Trust against the Income Tax Officer Exemption Ward 2(4), Mumbai, challenging an order dated November 11, 2025, passed by the Additional/Joint Commissioner of Income Tax (Appeals), Mysore, for the Assessment Year 2021-22.
On January 1, 2022, the assessee had filed its income tax return (ITR) for the year in consideration within the statutory due date, i.e., before March 15, 2022, as set by the CBDT vide its Circular No. 01/2022 [F. No. 225/49/2021/ITA-II], dated January 11, 2022. During the assessment of the return, the Assessing Officer (AO) denied the Section 11 exemption on the grounds that Form 10B was filed late on February 19, 2022.
The assessee argued that it attempted to furnish Form 10B on January 11, 2022; however, due to the technical glitches in the income tax portal, the form could not be reflected on the portal, which resulted in a significant delay. However, the form was later uploaded on the portal. Originally, the return was processed and an exemption was granted by the CPC under Section 143(1). Later, the department had passed a rectification order withdrawing the Section 11 exemption under Section 154, claiming it was mistakenly allowed previously.
When the tribunal analysed the facts of the case, it noted that the issue of Form 10B late filing had already been examined during the initial assessment of the return, and also the delay caused due to technical glitches in the portal was genuine. Further, it held that it is not allowed to reopen the matter under Section 154, which amounted to reviewing a decision, as rectification applies only to clear and obvious mistakes. The tribunal further noted that the assessee was not given any opportunity of hearing before issuing the rectification order, which reflects an explicit violation of the principles of natural justice. It held that the department acted incorrectly in withdrawing the exemption.
Considering the aforementioned findings, the tribunal set aside the impugned rectification order and restored the Section 11 exemption. In the end, the assessee's appeal was allowed.
About Author


Saloni Kumari
Content Writer
Saloni is a Content Writer with 2+ years of experience at studycafe.in. She writes legal, taxation, and finance related content including GST, Income Tax etc. Skilled in translating complex judicial pronouncements and regulatory developments into clear, and reader-friendly articles. Experienced in covering judgements of ITAT, High Court, GSTAT, and news related to Income Tax, GST, and corporate law. She can be reached at [email protected].
Saloni is a Content Writer with 2+ years of experience at studycafe.in. She writes legal, taxation, and finance related content including GST, Income Tax etc. Skilled in translating complex judicial pronouncements and regulatory developments into clear, and reader-friendly articles. Experienced in covering judgements of ITAT, High Court, GSTAT, and news related to Income Tax, GST, and corporate law. She can be reached at [email protected].
 StudyCafe
 Delhi, Delhi, India
 2847
My Recent Articles
- NU Vista Receives Rs 24.98 Crore Tax Demand Show Cause Notice for FY 2022-23 Over Yield Calculation and Moisture Loss
- Ramco Systems’ Philippines Subsidiary Settles Tax Demand at PHP 3 Mn Against Original PHP 72.40 Mn Claim
- Mahindra Holidays Receives GST Show Cause Notice Proposing Rs 36.29 Crore Demand for FY 2022-23
- Govt Extends RoDTEP Scheme for Exporters Till Dec 31, 2026, Existing Rates and Value Caps Remain Unchanged
- ICAI Proposes Rs 5 Crore Government Consultancy Tenders Reservation for Firms with Lower Net Worth
Up Next
Loading suggestions…


Recent Posts
All Posts
Recent Posts
All Posts