ITAT Rejects Trust’s Appeal Against Section 12A Registration Renewal Denial After Eight Hearing Opportunities:
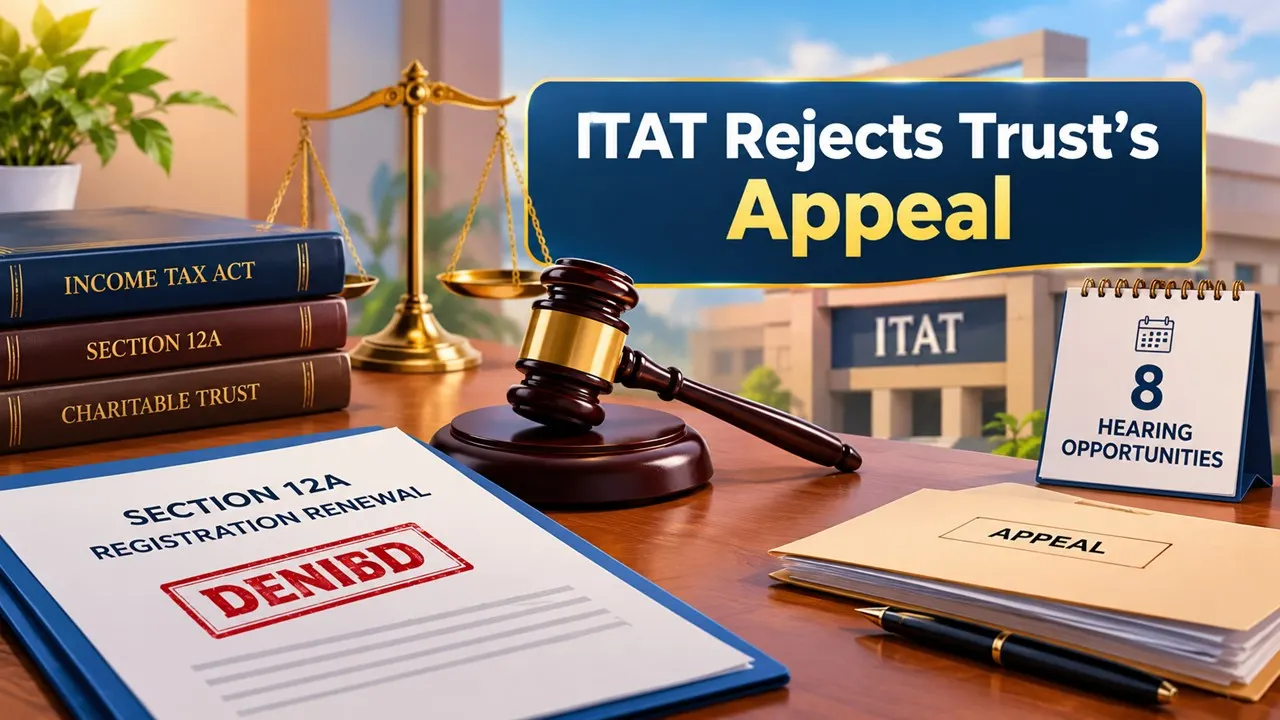
The ITAT dismissed appeal against the rejection of its Section 12A registration renewal application after the trust failed to attend eight hearings or submit the required documents.
Appeal Dismissed Due to Repeated Non-Compliance by Trust
 Saloni Kumari
 Oct 12, 2026

The ITAT Ahmedabad Bench has dismissed an appeal filed by a charitable trust against the rejection of its application for renewal of registration under Section 12A(1)(ac)(ii) of the Income Tax Act, 1961. The Tribunal dismissed the appeal because the trust repeatedly failed to appear for hearings or submit the required documents.
Shri Bayad Stand Vaishnav Pushtiy Margiy Shree Vallabh Seva Trust, a religious and charitable organisation from the Bayad region of Gujarat, had filed an application in Form No. 10AB, seeking registration renewal under Section 12A(1)(ac)(ii) of the Act.

The Commissioner of Income Tax (Exemption) [CIT(E)] had asked the assessee to furnish certain relevant details to verify the genuineness of the trust's activities and whether they were consistent with its charitable objectives. For the same, the CIT(E) had provided the trust two opportunities on July 16, 2025, and September 03, 2025. However, the assessee remained non-compliant.
Consequently, the CIT(E), vide an order, rejected the trust's application. The trust, being aggrieved by the CIT(E)'s order, challenged the same before the Income Tax Appellate Tribunal (ITAT), Ahmedabad.
During the personal hearings, none appeared on behalf of the assessee. The hearings were scheduled on 04.02.2026, 10.03.2026, 15.04.2026, 12.05.2026, 15.06.2026, 30.06.2026, 18.08.2026 and 22.09.2026. Hence, in total, the trust was granted eight opportunities of hearings. However, the trust was non-compliant.

The Tribunal noted that notices during the personal hearings were communicated to the trust through email and physical service, but the trust neither appeared nor filed written submissions or supporting documents.
The Tribunal observed that, in the absence of the necessary evidence, it could not properly examine the issues raised or consider restoring the matter to the CIT(E) for fresh consideration. It concluded that the trust was not interested in pursuing the appeal and dismissed it for non-prosecution.
About Author

Saloni Kumari
Content Writer
 StudyCafe
 Delhi, Delhi, India
 3000
My Recent Articles
- CBIC Invites Public Consultation on Alternate Mechanism for Amendment of Liability and ITC in FORM GSTR-3B
- CBDT Notifies New Rules for Merger of Registered Non-Profit Organisations Under Income Tax Rules 2026
- Avathon and SparkCognition Withdraw Arbitration Proceedings Against Aditya Infotech After Mutual Discussion
- CBIC Orders Interim GST Reforms: No Arrests, Limited E-Way Bill Checks and Rs 10,000 SCN Limit
- GST Council Releases Minutes Book and Agenda Notes (Volumes I & II) of 56th GST Council Meeting
Loading suggestions…


Recent Posts
All Posts
Recent Posts
All Posts