ITAT Rules Late Form 10B Filing Cannot Deny Section 11 Exemption; Tribunal Favours Assessee:
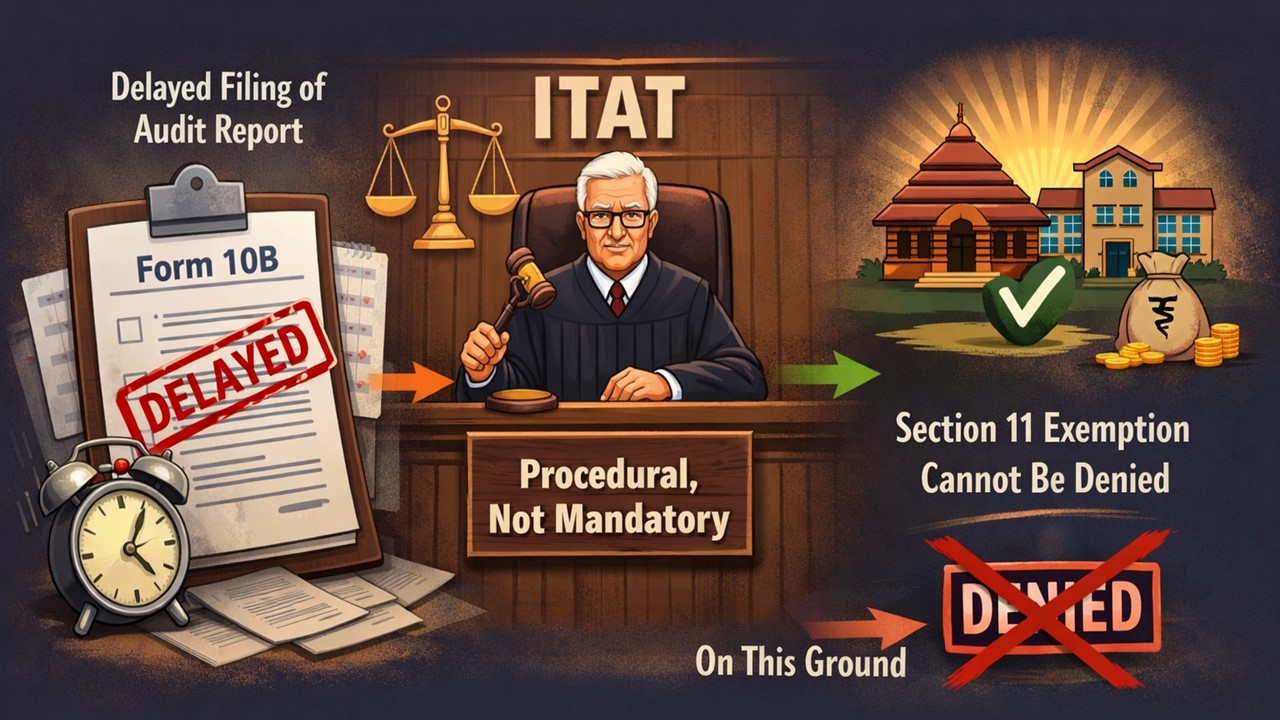
ITAT holds that the delayed filing of the audit report in Form 10B is procedural, not mandatory, and the Section 11 exemption cannot be denied on this ground.
ITAT Sets Aside CIT(A) Order Over Procedural Delay in Form 10B
 Saloni Kumari
 Dec 22, 2025

ITAT Rules Late Form 10B Filing Cannot Deny Section 11 Exemption; Tribunal Favours Assessee
Father Leblond Trust filed the present appeal before the ITAT Kolkata, challenging an order passed by the CIT(A)/NFAC Delhi on December 20, 2024, under Section 250 of the Income Tax Act, 1961. Through the impugned order, CIT(A) had denied the trust's availed exemption under Section 11 of the Act.
The assessee is an approved trust under Section 12A of the Act. The trust filed its return of income under section 139(4A) exactly on the extended statutory due date, i.e., October 31, 2019, and also submitted an audit report in Form No. 10BB dated September 25, 2019. The tax authorities denied the assessee's claim of exemption under section 11 of the Act vide rectification order dated October 30, 2020.
The main reason behind the denial was the late filing of the audit report in Form 10B, even though the return and Form 10BB were timely furnished. The aggrieved assessee filed an appeal before CIT(A). However, CIT(A) dismissed the appeal of the assessee through the impugned order dated December 20, 2024. Thereafter, the assessee filed an appeal before the ITAT Kolkata. The initial appeal was delayed by 140 days, but the Tribunal condoned it due to the trustee’s health issues.
The trust argued that the filing of Form 10B is only a procedural requirement, not a compulsion, and a delay should not be the mere reason to deny the exemption. The tribunal endorsed this argument of the assessee that filing Form 10B is procedural, and that the exemption under Section 11 cannot be denied just because it was filed late. It noted that the intimation under Section 143(1) was incorrect in denying the exemption.
As a result, the Tribunal set aside the impugned CIT(A) order and directed the AO/CPC to consider the audit report and grant the assessee exemption under Sections 11 and 12. The appeal was partly allowed for statistical purposes.
About Author

Saloni Kumari
Content Writer
Saloni is a Content Writer with 2+ years of experience at studycafe.in. She writes legal, taxation, and finance related content including GST, Income Tax etc. Skilled in translating complex judicial pronouncements and regulatory developments into clear, and reader-friendly articles. Experienced in covering judgements of ITAT, High Court, GSTAT, and news related to Income Tax, GST, and corporate law. She can be reached at [email protected].
Saloni is a Content Writer with 2+ years of experience at studycafe.in. She writes legal, taxation, and finance related content including GST, Income Tax etc. Skilled in translating complex judicial pronouncements and regulatory developments into clear, and reader-friendly articles. Experienced in covering judgements of ITAT, High Court, GSTAT, and news related to Income Tax, GST, and corporate law. She can be reached at [email protected].
 StudyCafe
 Delhi, Delhi, India
 2819
My Recent Articles
- Zila Tax Bar Association Seeks Extension of Tax Audit Report Due Date Until October 31, Citing Compliance Challenges
- GSTAT Releases Inaugural E-Journal Featuring 20 GST Cases and 7 Anti-Profiteering Cases
- CBI Arrests Key Accused in US$7.21 Million Transnational Cyber Fraud Case
- Best Salary Accounts for Corporate Employees: Zero AMB, Free Debit Card & Cashback
- Income Tax Dept Reminds Taxpayers to Complete TAR Filing Process Before Sept 30, to Avoid Last Minute Hustle
Up Next
Loading suggestions…


Recent Posts
All Posts
Tags
Recent Posts
All Posts