ITAT Upholds 28.59 Lakh Addition on Taxpayer for Unexplained Cash Deposits; Appeal Dismissed:
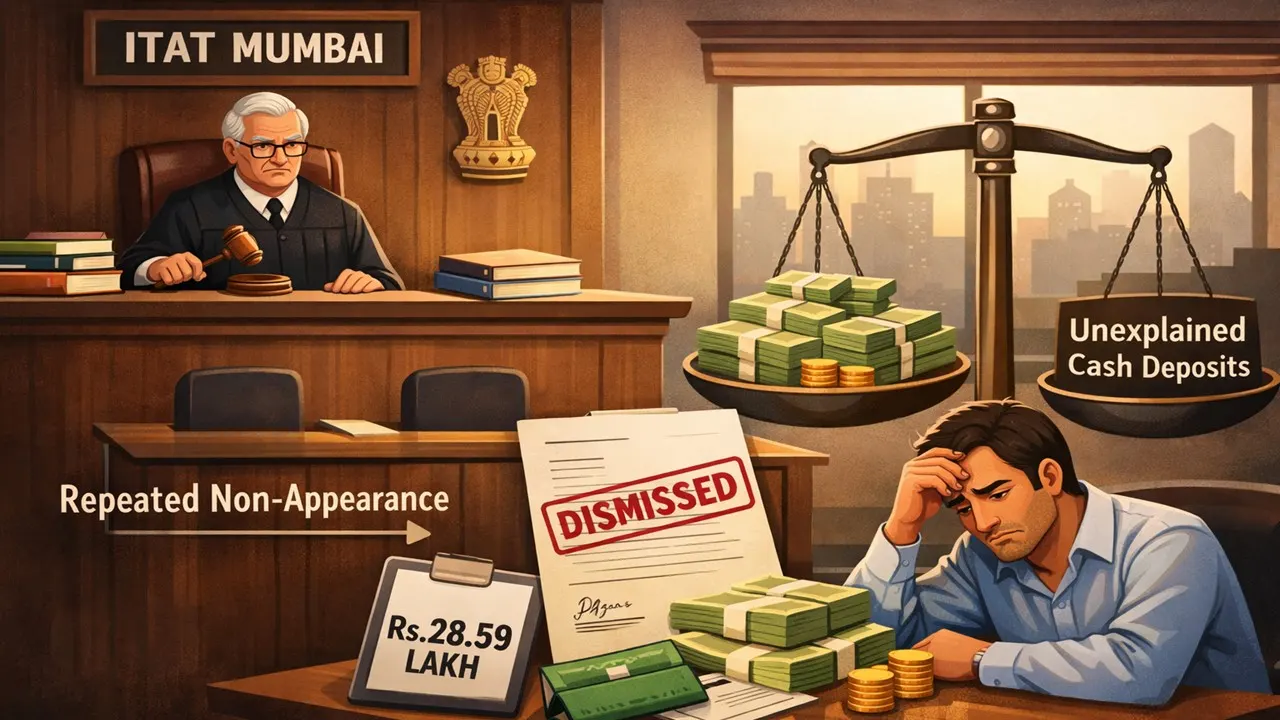
ITAT Mumbai dismissed the taxpayer’s appeal for repeated non-appearance, upholding a Rs. 28.59 lakh addition for unexplained cash deposits.
ITAT Mumbai Rejects Taxpayer’s Appeal Over Failure to Respond to Notices
 Saloni Kumari
 Jan 7, 2026

ITAT Upholds 28.59 Lakh Addition on Taxpayer for Unexplained Cash Deposits; Appeal Dismissed
ITAT Mumbai dismissed the taxpayer’s appeal as he repeatedly failed to respond to notices or attend hearings. The reassessment for unexplained cash deposits resulted in an addition of Rs. 28.59 lakh, upheld due to non-prosecution.
The present appeal has been filed by a taxpayer named Mahesh Narsinghani in the ITAT Mumbai, challenging an order dated February 04, 2025, passed by the CIT(A)/NFAC, Delhi. The impugned order had dismissed the appeal of the assessee, as he did not answer to any of the notices issued by them.
The assessee electronically filed his income tax return (ITR) for the assessment year 2017-18, declaring 'zero' taxable income. The case was later reopened by the Assessing Officer (AO) under Section 148 of the Income Tax Act, on the grounds of the fact that the assessee had deposited substantial cash in his bank accounts in Bank of Baroda, J&K Bank, and Kotak Mahindra Bank during the year in consideration.
As a result, a notice was issued to the assessee. However, the assessee did not file any return in response to the Section 148 notice. Additionally, he did not respond to the notice issued under Section 142(1) of the Act. In conclusion, the AO issued the final order dated May 22, 2023, under Sections 147/144/144B, without hearing the side of the assessee, making an addition of Rs. 28,59,760 to the assessee's income.
The tribunal scheduled the personal hearing on 16.07.2025, 21.08.2025, 08.10.2025, 16.12.2025, and 23.12.2025. However, the assessee only appeared for the first hearing and furnished letters for adjournment for the subsequent two hearing dates. No one attended the remaining hearings. As per the law, the tribunal has the power to dismiss any appeal in case the assessee did not present its side despite being given several reasonable opportunities. Therefore, the tribunal dismissed the present appeal of the assessee.
About Author


Saloni Kumari
Content Writer
Saloni is a Content Writer with 2+ years of experience at studycafe.in. She writes legal, taxation, and finance related content including GST, Income Tax etc. Skilled in translating complex judicial pronouncements and regulatory developments into clear, and reader-friendly articles. Experienced in covering judgements of ITAT, High Court, GSTAT, and news related to Income Tax, GST, and corporate law. She can be reached at [email protected].
Saloni is a Content Writer with 2+ years of experience at studycafe.in. She writes legal, taxation, and finance related content including GST, Income Tax etc. Skilled in translating complex judicial pronouncements and regulatory developments into clear, and reader-friendly articles. Experienced in covering judgements of ITAT, High Court, GSTAT, and news related to Income Tax, GST, and corporate law. She can be reached at [email protected].
 StudyCafe
 Delhi, Delhi, India
 2931
My Recent Articles
- Rs 843.97 Crore Bogus Political Party Donation Racket Unearthed in Gujarat, Income Tax Dept Files Complaint With CID (Crime)
- Retired Central GST Commissioner Kidnapped by Unknown Persons, Assailants Nabbed Within Hours
- Madhya Pradesh HC Quashes Section 74 GST Show Cause Notice Passed Against G R Infraprojects
- GSTAT Introduces SOP for Branch Officer-to-Branch Officer (BO-to-BO) Case Transfer Ensuring Seamless Reassignment of Cases
- GSTAT: E-Way Bills Cannot Be Invalidated Merely Because They Were Not Generated by Original Supplier
Up Next
Loading suggestions…


Recent Posts
All Posts
Tags
Recent Posts
All Posts