Section 54 LTCG Exemption: Can You Claim It by Buying a Plot?:
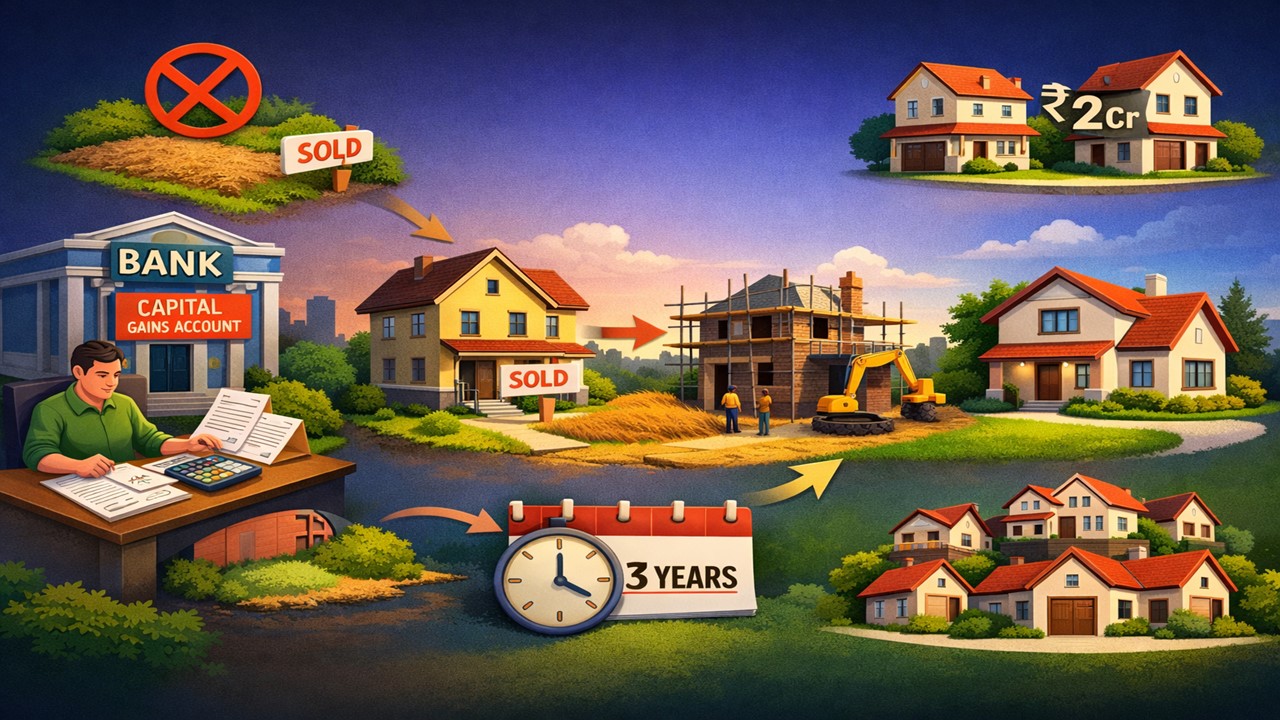
You can’t claim LTCG exemption by just buying a plot of land; you must construct a Residential House within 3 years.
Key Rules Every Taxpayer Should Know
 Vanshika verma
 Mar 2, 2026

Section 54 LTCG Exemption: Can You Claim It by Buying a Plot?
Section 54 provides exemption from long-term capital gains (LTCG) tax when an individual or Hindu Undivided Family (HUF) sells a residential house property and reinvests the capital gains in another residential house in India.
However, several taxpayers still have confusion about this section 54. One major question is whether an exemption under Section 54 of the Income-tax Act, 1961, can be claimed if a person sells a residential apartment and purchases only a plot of land.
The answer is no, buying just a plot does not qualify for exemption because Section 54 requires investment in a residential house. However, if you sell a house and make a long-term capital gain (LTCG), you can save tax by buying a plot and building a new residential house on it. But the construction must be completed within three years from the date you sold the original house.
If you are not able to use the whole capital gain amount before the due date of filing your Income Tax Return (ITR), then the unused amount should be deposited in a bank account under the Capital Gains Account Scheme. The money kept in this account must then be used to buy or construct the new house within the prescribed time period.
Another confusion of taxpayers is about how many times they can claim exemption on long-term capital gains (LTCG) from the sale of a residential property. The provision allows an individual to claim exemption if the capital gains from selling a residential house are reinvested in another residential house in India.
The once-in-a-lifetime restriction is only applicable if the amount of LTCG does not exceed Rs. 2 crore in two residential houses in India.
However, apart from this specific case, there is no limit on the number of times a person can claim exemption under Section 54, as long as the long-term capital gains are reinvested in another residential property as per the prescribed conditions.
About Author

Vanshika verma
Content Writer
Vanshika Verma is a Content Writer with 1+ year of experience at Studycafe.in. A B.Com graduate from Delhi University, She writes articles on Finance, Tax, ICAI, GST, and the latest financial news, with a focus on making complex topics easy for readers and professionals.
Vanshika Verma is a Content Writer with 1+ year of experience at Studycafe.in. A B.Com graduate from Delhi University, She writes articles on Finance, Tax, ICAI, GST, and the latest financial news, with a focus on making complex topics easy for readers and professionals.
 Studycafe
 Delhi, Delhi, India
 1985
My Recent Articles
- Vikran Engineering Receives Rs 1.55 Crore GST Notice Including Rs 83.62 Lakh Tax Demand, Interest and Penalty
- Fire Officer Allegedly Demanded Rs 3 Lakh for School NOC, Caught Accepting Rs 1 Lakh in Lokayukta Trap
- Telangana GST Fraud: CGST Unearths Rs 5.68 Crore Tax Evasion Through Alleged Fake SEZ Registration, Proprietor Arrested
- Mahadev Betting Case: CBI Arrests Key Accused Abhishek Kumar After UAE Deportation, ED Flags Rs 94,000 Crore Illegal Money Trail
- Court Allows 7 Arrested Foreigners To Travel Abroad For A Month To Meet Their Families
Up Next
Loading suggestions…


Recent Posts
All Posts
Recent Posts
All Posts