Borrowed Satisfaction Cannot Justify Section 147 Reassessment, Rules ITAT Delhi:
The ITAT Delhi deleted the Rs 72.45 crore addition, holding that reopening under Section 147 cannot be based on “borrowed satisfaction".
ITAT Deletes Rs 72.45 Crore Addition Under Section 68
 Saloni Kumari
 May 22, 2026

Borrowed Satisfaction Cannot Justify Section 147 Reassessment, Rules ITAT Delhi
The ITAT Delhi has recently held in favour of Peakwood Reality Private Limited by deleting the impugned addition amounting to Rs 72.45 crore made by the Income Tax Authorities under Section 68 of the Income Tax Act on the grounds that the loans received by the company from Focus Realcon Private Limited and Starlite Builders Private Limited were bogus accommodation entries linked to the M3M Group investigation.
When the assessee, Peakwood Reality Private Limited, challenged the Rs 72.45 crore addition before the ITAT Delhi, the tribunal noted that the tax authorities had reopened the case merely based on the information received from the Investigation Wing without conducting any independent inquiry. Consequently, the tribunal held that reopening under Section 147 cannot be based on “borrowed satisfaction", and there must be a direct link between the material available and the belief that income escaped assessment. Since the department failed to provide the underlying investigation material to the assessee and did not conduct fresh verification, the reassessment proceedings were consequently declared invalid.
When the tribunal analysed the case on its merits, it observed that the assessee had furnished all the relevant evidence proving the genuineness of the loans taken by it, including bank statements, confirmations, income tax returns, financial statements, and Memorandums of Understanding (MOUs) showing that the money was received as advances for land procurement and development projects. Furthermore, the transactions in question were made through banking channels, and the amounts were later repaid, which supported the genuineness of the transactions.
It was further noted that statements on which the tax authorities had relied were given by individuals who were no longer directors of the lender companies during the year in consideration, making such statements unreliable. To announce the final decision, the tribunal cited several earlier judgements of the High Court and the Supreme Court in cases based on a similar issue and held that the assessee had successfully proved the identity, genuineness, and creditworthiness of the lenders. In conclusion, the impugned addition amounting to Rs 72.45 crore was deleted in full, and the appeal was allowed.

About Author


Saloni Kumari
Content Writer
Saloni is a Content Writer with 2+ years of experience at studycafe.in. She writes legal, taxation, and finance related content including GST, Income Tax etc. Skilled in translating complex judicial pronouncements and regulatory developments into clear, and reader-friendly articles. Experienced in covering judgements of ITAT, High Court, GSTAT, and news related to Income Tax, GST, and corporate law. She can be reached at [email protected].
Saloni is a Content Writer with 2+ years of experience at studycafe.in. She writes legal, taxation, and finance related content including GST, Income Tax etc. Skilled in translating complex judicial pronouncements and regulatory developments into clear, and reader-friendly articles. Experienced in covering judgements of ITAT, High Court, GSTAT, and news related to Income Tax, GST, and corporate law. She can be reached at [email protected].
 StudyCafe
 Delhi, Delhi, India
 2825
My Recent Articles
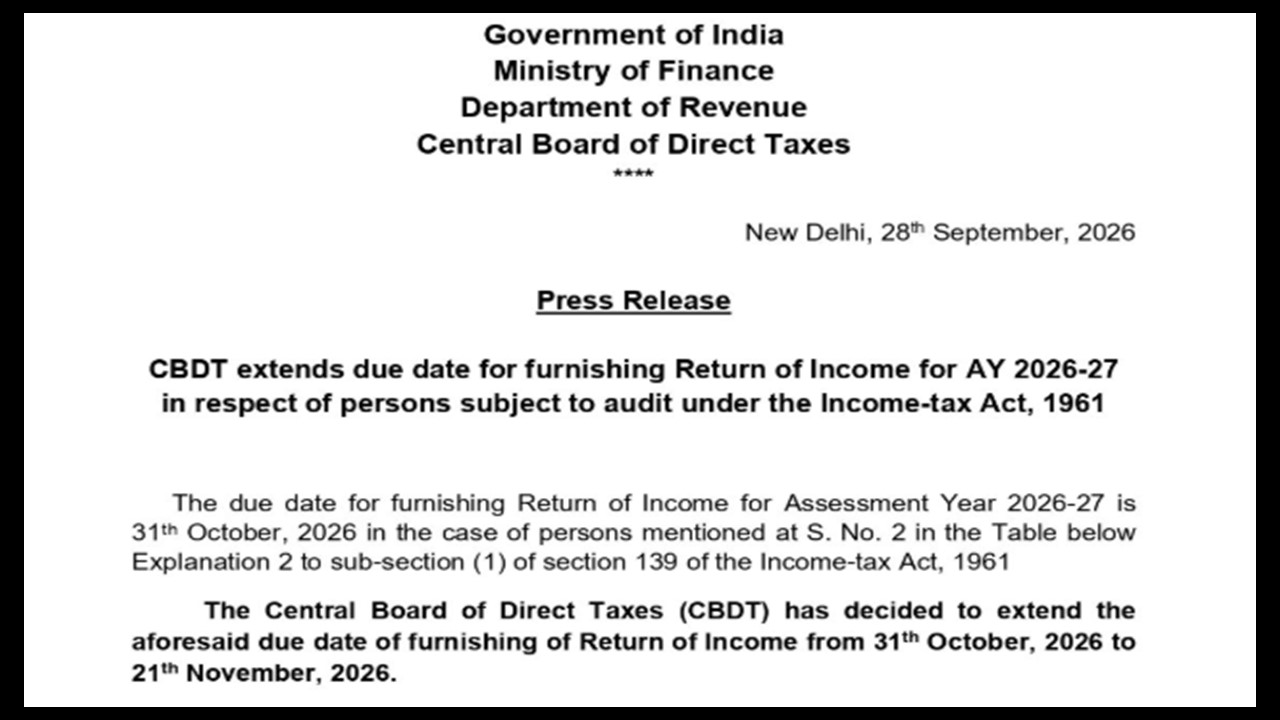
- CBDT Extends Income Tax Return and Tax Audit Report Filing Deadlines for AY 2026-27
- ITAT Remands Appeal of Unexplained Investments and Loans After CIT(A) Allegedly Overlooked Submitted Evidence
- ITAT Allows Section 54F Deduction for Two Bungalows Clubbed as Single Residential Unit
- ITAT Upholds PCIT's Section 263 Revision Over AO's Incomplete Inquiry into Bogus Purchases
- CBI Arrests Two in Rs 11.42 Crore Cyber Fraud Network, Raids 22 Premises in 10 States under Operation Chakra VI
Up Next
Loading suggestions…


Recent Posts
All Posts
Recent Posts
All Posts